Swiss fintech
Visa and Mastercard bring simpler international transfers to Swiss banking apps
Visa and Mastercard are joining the Swiss Payinit platform to let customers send international transfers through their existing banking apps using a mobile number or email address. The article should explain how the system works, which payment options are supported and what it could mean for competition, fees and consumer protections in cross-border payments.
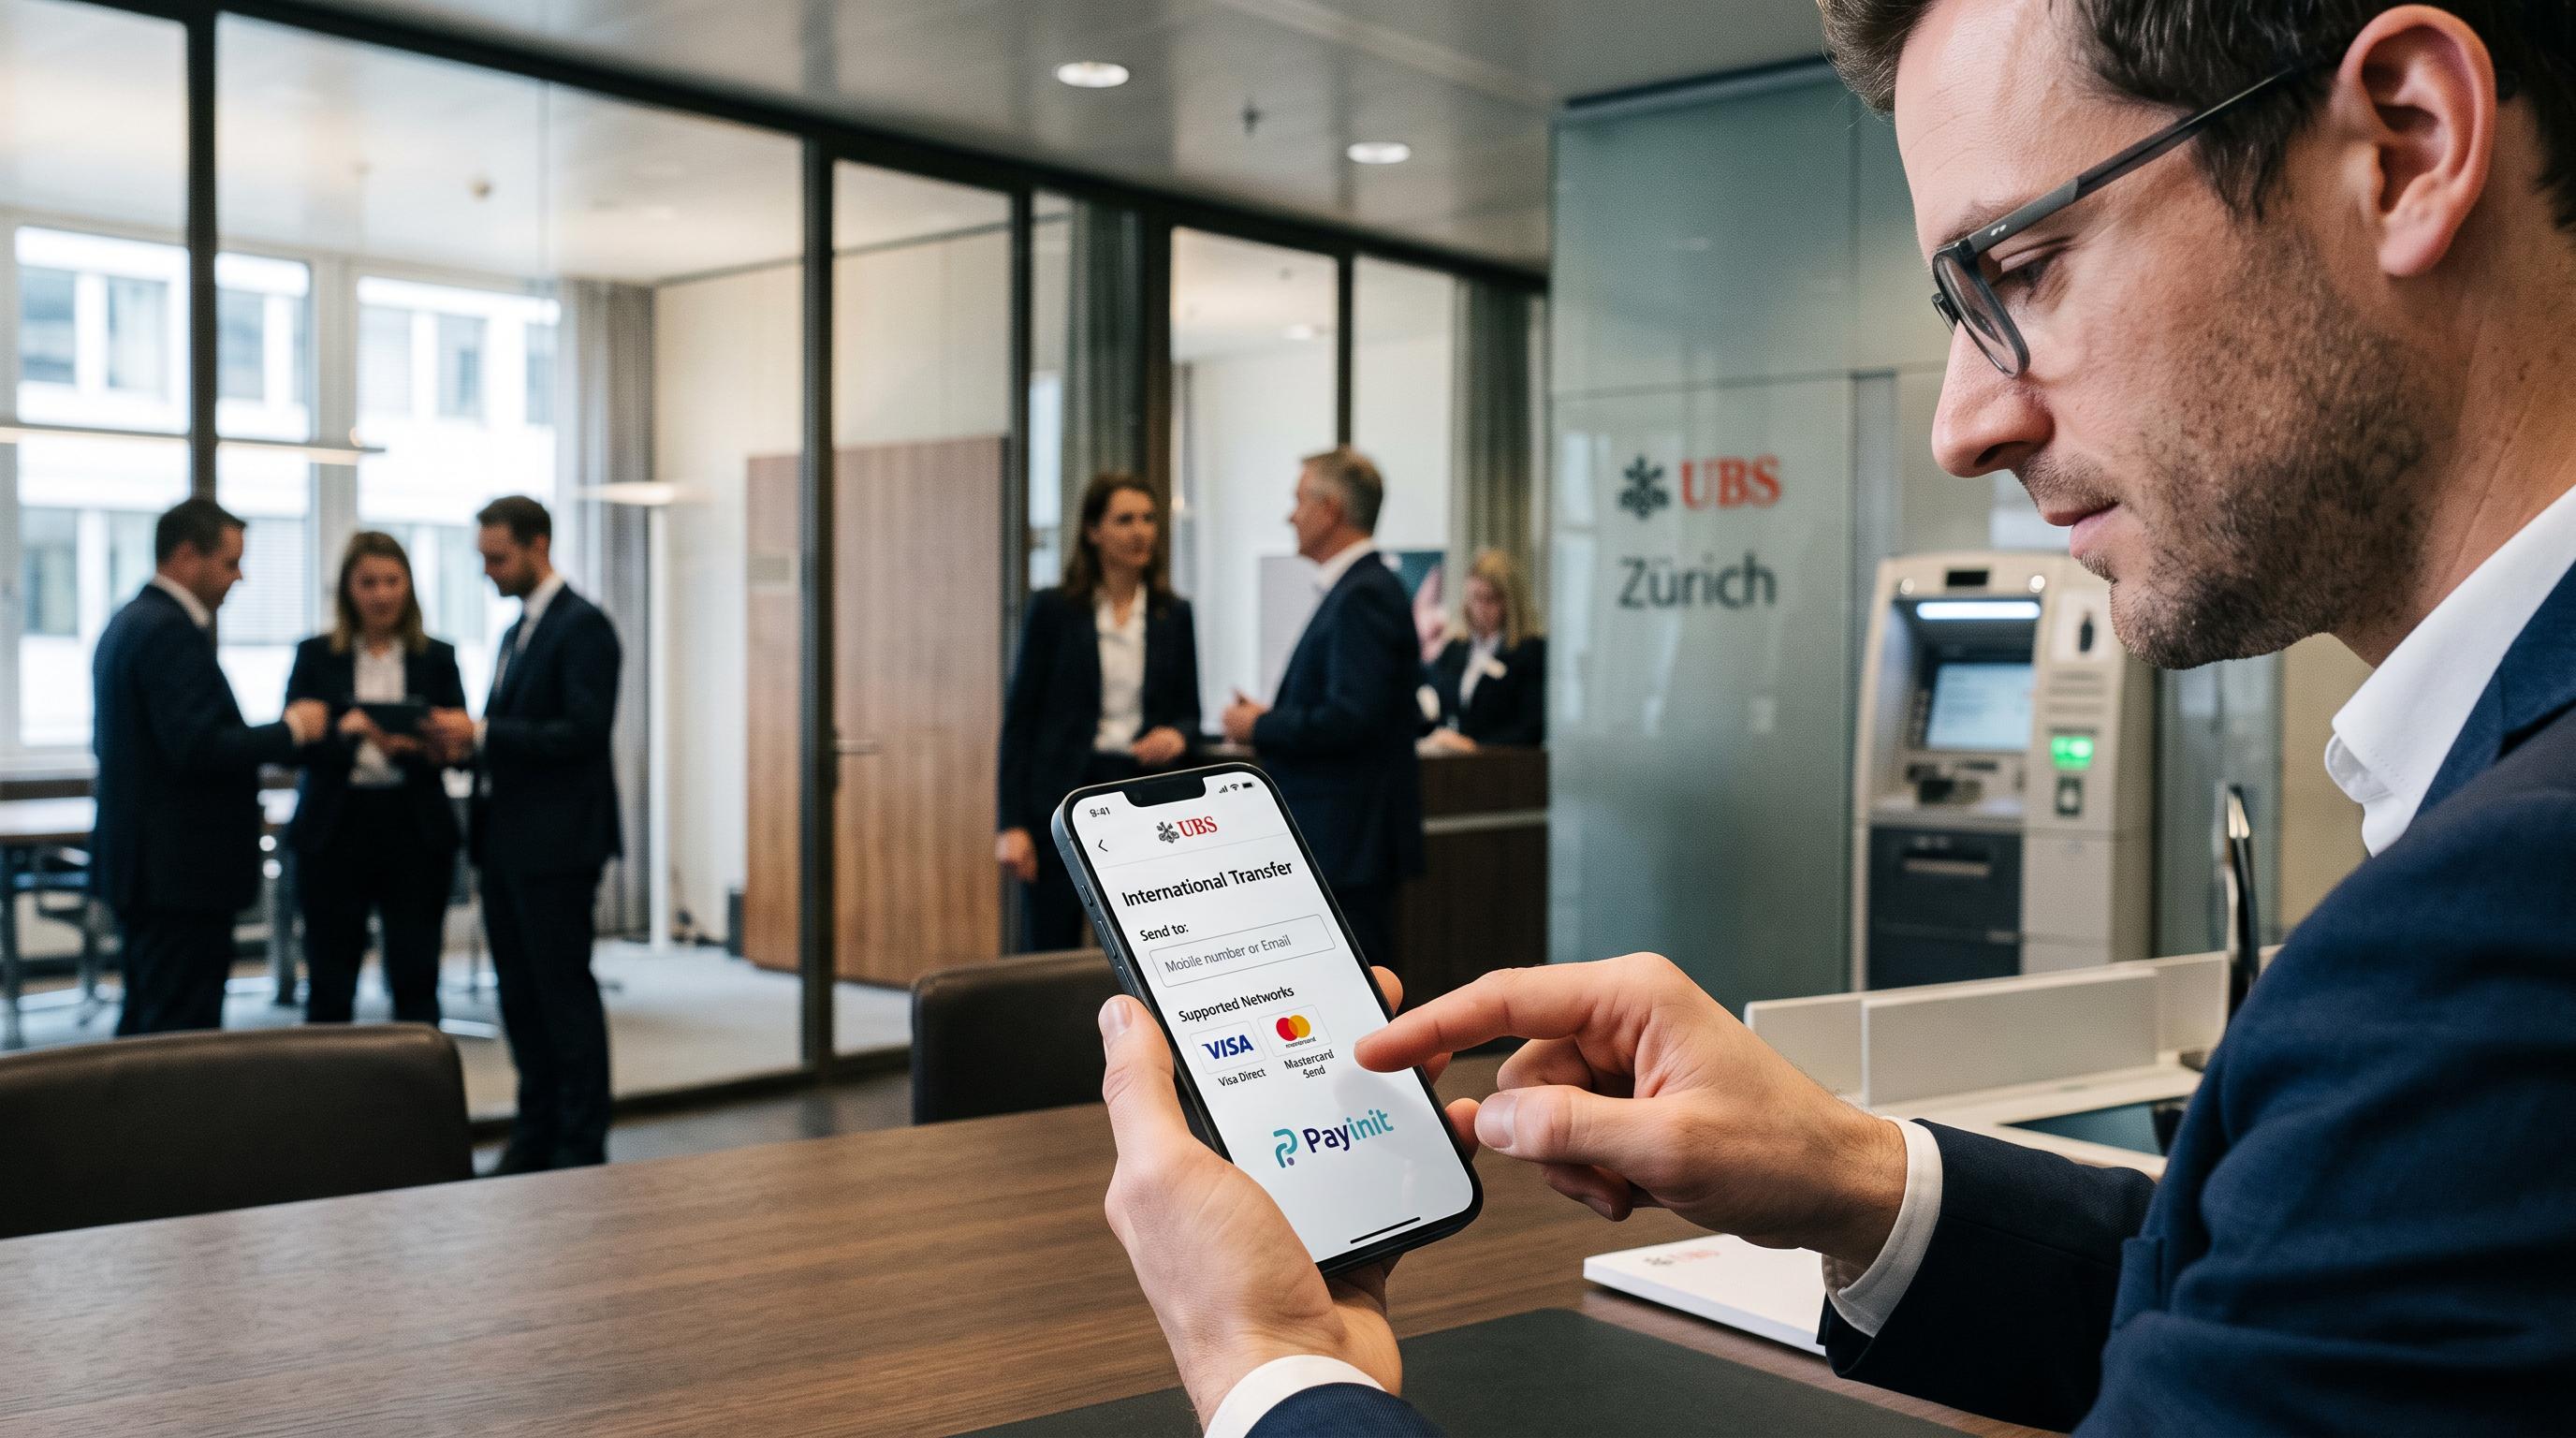
Swiss banking apps open a simpler route abroad
Swiss bank customers could soon send money abroad with the ease of sharing a contact. Visa and Mastercard are working with Payinit, a Swiss joint venture owned by Viseca and Cornèr Bank, to bring international transfer functions into existing banking and payment apps.
The proposal targets a familiar problem for people in Switzerland: sending money across borders can require bank details, card information and separate payment services. Under the Payinit model, a sender would use a mobile number or email address linked to the recipient. The money could then be delivered to a payment card, a bank account or a digital wallet, depending on the service and destination.
The announcement, published on August 31, 2026, does not describe a new standalone app for consumers. Payinit is building shared infrastructure that Swiss banks and card issuers can connect to their own digital offerings. Customers would continue to start the transaction inside the app they already use.
Santosh Ritter, Visa Switzerland's head, said cross-border person-to-person payments are often “slow and cumbersome”. The partnership places that friction at the centre of a fast-growing contest over how consumers move money internationally.
Payinit connects four payment services
Four named services will underpin the new transfer network: Visa Direct, Visa+, Mastercard Move and Mastercard Credential Services. Together, they give participating Swiss institutions access to international payment rails without requiring each bank to build separate technical connections to Visa and Mastercard.
That shared architecture is the practical role Payinit is designed to play. The platform acts as a common integration layer between Swiss banks or other issuers and the card networks. Opentech will provide the technical infrastructure, while the customer relationship remains with the bank or payment provider presenting the feature.
The recipient's endpoint will determine how the transaction works. A transfer may arrive on a payment card, in a bank account or in a digital wallet. The source material does not specify which countries, currencies or corridors will be supported at launch. It also does not state how quickly funds will arrive in each destination.
That flexibility could make the service useful for remittances, family support, travel payments and small business transactions. It also means customers will need clear information before confirming a payment. A familiar contact method does not by itself reveal the exchange rate, the receiving institution or the final delivery time.
Competition will decide the price
The platform's open-access design could sharpen competition among Swiss banks, card issuers and payment apps. Payinit is intended to be available to all Swiss card issuers and mobile payment providers, rather than serving only the institutions behind its creation.
For banks, the attraction is speed and scale. They can add international transfer capabilities without negotiating and maintaining their own technical links to both global card networks. Smaller providers may gain access to infrastructure that would otherwise be expensive to develop. Customers could see more transfer options appear inside familiar Swiss apps, including services that compete on speed, convenience or destination coverage.
The commercial details remain unsettled. The announcement provides no fee schedule, foreign exchange margin, minimum transfer amount or delivery guarantee. It also does not say whether a bank, Payinit, a card network or a receiving provider will set the final price. Those details will determine whether the new interface produces meaningful savings or simply makes existing costs easier to access.
Daniela Massaro, Mastercard Switzerland's head, said customers expect transfers to be “as easy as sending a message anywhere in the world”. The competitive test will be whether providers can match that simplicity with transparent pricing.
Simple sending needs strong safeguards
A mobile number can remove paperwork, but it cannot remove the need for safeguards. The Payinit announcement describes a smoother way to identify a recipient, yet it does not set out new rules for mistaken payments, fraud, account takeovers, refunds or disputes.
Those protections will matter because a contact-based transfer can feel more informal than a traditional bank payment. Before sending money, users should be shown the recipient's verified name, the amount in Swiss francs and the destination currency, along with the exchange rate, total charges and expected delivery time. Providers should also make clear whether the transfer can be cancelled and who handles a complaint if the money reaches the wrong account or wallet.
The route matters as well. A payment sent to a card may operate under different rules from one sent to a bank account or digital wallet. The announcement does not identify the participating institutions, supported countries or applicable fee and dispute policies. Swiss customers will therefore need to read the terms supplied by their own bank or payment provider.
Payinit's shared infrastructure could make cross-border transfers easier to access. Its consumer value will depend on how clearly providers explain the risks and costs behind the simple contact lookup.
Switzerland's payment apps look beyond borders
Switzerland's payment market is moving toward more services inside everyday apps. The Payinit initiative arrives as Swiss providers expand beyond domestic payments and traditional card use. Its model could give banks a practical way to offer international transfers while keeping customers within their existing digital relationship.
The timing also places the project alongside other changes in Swiss fintech. Twint, the country's best-known mobile payment app, is scheduled to launch direct debit in 2027, according to a separate Swissinfo report. That development and Payinit's international focus point to a broader expansion of what consumers expect from payment apps.
The next milestones will be operational rather than promotional. Payinit and its participating providers will need to disclose launch dates, supported corridors, currencies, fees, foreign exchange rates and customer protection procedures. They will also need to explain how recipients are verified when a sender relies on an email address or mobile number.
If banks deliver those details clearly, Swiss customers could gain a more convenient route for everyday cross-border payments. If costs or restrictions remain difficult to compare, the new interface may simplify the button presses without simplifying the decision.