Switzerland
FINMA says PostFinance crisis plans still need work
FINMA says PostFinance still needs to clarify its plans for dealing with a severe financial crisis, even though the bank has met requirements for loss-absorbing capital. Zurich Cantonal Bank and Raiffeisen, by contrast, were judged to have met the regulator’s requirements.
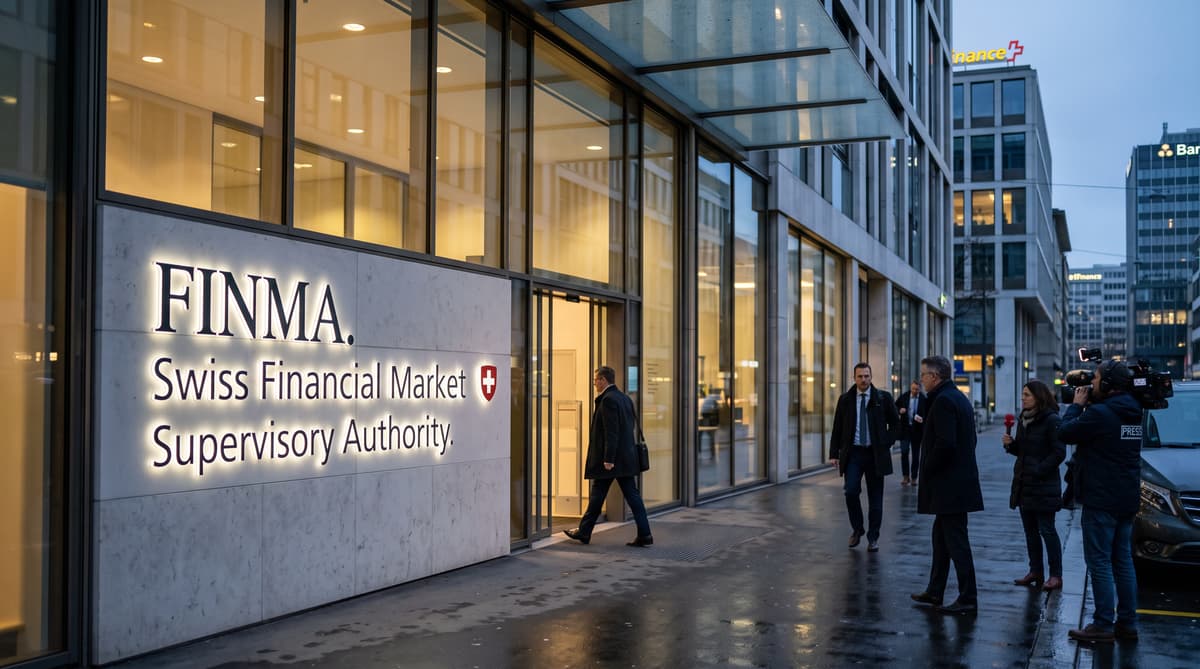
FINMA has accepted PostFinance’s capital position, but not the bank’s full emergency playbook. Switzerland’s financial regulator said on October 14, 2026 that the state-owned bank has met requirements for additional loss-absorbing capital since the end of 2025. PostFinance has also developed an alternative strategy for a severe financial crisis.
The unresolved issue concerns the measures available if the bank cannot be stabilised, restructured or kept operating. FINMA said those options still require further specification. The finding leaves PostFinance with more work to do before the regulator can regard its contingency arrangements as fully convincing.
The issue matters beyond PostFinance’s balance sheet. The bank carries out services linked to the Swiss postal system and remains subject to a statutory universal service obligation. Any emergency plan must therefore address how essential services would continue during a disorderly failure or major restructuring.
FINMA’s assessment covers the plans submitted in 2025. It also reflects the tougher supervisory standards introduced after Credit Suisse collapsed and UBS took over the failed lender in 2023. The regulator’s message is precise: capital provides resilience, while a workable plan must explain what happens when resilience runs out.
FINMA demands clearer last resort options
PostFinance must spell out its last-resort options more clearly. FINMA’s concern focuses on the stage of a crisis when ordinary stabilisation measures no longer work and the bank cannot continue in its existing form. The regulator did not publish a detailed list of missing measures, but it said the alternatives in that scenario must be further specified.
That requirement forces the bank to connect its financial planning with the legal duties attached to its public role. PostFinance is Switzerland’s postal bank, and its statutory universal service obligation creates uncertainty about how essential payment and account services would be maintained if the institution faced failure.
The Federal Council is consulting on an amendment to the Postal Services Act. FINMA said the proposed change should reduce legal uncertainty around the obligation. The legislative process could therefore shape the assumptions behind PostFinance’s revised emergency plan.
The regulator assesses two linked documents each year. A stabilisation plan sets out how a bank could restore financial strength and continue critical operations. An emergency plan addresses the steps available if that effort fails. For PostFinance, FINMA has acknowledged progress on the first part while demanding more precision on the second.
Two Swiss banks meet FINMA requirements
Zurich Cantonal Bank and Raiffeisen cleared the same regulatory review. FINMA said the two other domestically focused systemically important banks met its requirements for contingency planning. The three institutions share a special status because their failure could disrupt the Swiss economy and payment system.
The comparison does not mean the banks face identical risks or operate with identical structures. Zurich Cantonal Bank is rooted in the canton of Zurich, while Raiffeisen is organised as a cooperative banking group with a broad network of local institutions. PostFinance has a different profile, including its connection to Swiss Post and its statutory service obligations.
FINMA reported progress in stabilisation planning across all three banks. It also identified remaining work under the revised requirements. The outstanding tasks include documenting crisis exercises and completing crisis communication plans. FINMA expects the banks to close those gaps promptly.
The regulator warned that approval of contingency plans does not guarantee that systemically important functions could continue without restriction in every conceivable crisis. The assessment confirms that planning has advanced, while leaving room for operational weaknesses to emerge under extreme pressure. Banks must demonstrate not only that plans exist, but that staff can execute them when markets, technology and public confidence come under strain.
Credit Suisse crisis reshaped bank supervision
Switzerland’s post Credit Suisse rulebook is testing whether banks can act before a collapse becomes unavoidable. FINMA tightened its expectations after the 2023 failure of Credit Suisse, when authorities arranged its takeover by UBS. The experience exposed the limits of relying on capital strength and broad assurances without fully tested execution plans.
The regulator now expects banks to document crisis exercises and prepare communication plans that can function during rapidly changing events. Those measures cover practical questions such as who makes decisions, how critical services are protected and how customers, employees and authorities receive reliable information.
Domestic systemically important banks have smaller financial buffers than globally active systemically important banks, according to FINMA. In an especially severe crisis, that narrower capacity could limit the choices available to management and authorities. A plan that works in a contained disruption may not survive a simultaneous run, market stress and operational failure.
FINMA will report separately on UBS’s crisis planning in late autumn 2026. That review will add the largest Swiss bank to the next stage of the country’s too big to fail debate. For PostFinance, the immediate task is narrower but consequential: clarify how the bank and the state would manage the point at which ordinary recovery measures fail.
PostFinance faces its next test in public service planning
PostFinance’s next plan will have to reconcile public service with crisis resolution. The bank has already satisfied the capital requirement FINMA highlighted, giving it a stronger financial buffer against losses. The remaining test concerns the legal and operational route through a failure scenario, particularly if the bank cannot be restored as a going concern.
The consultation on the Postal Services Act could provide a clearer framework. Until lawmakers settle the rules, PostFinance and the authorities must plan around uncertainty over how its universal service obligation would operate during a restructuring, transfer of activities or wind-down.
FINMA’s findings do not predict that PostFinance will fail. They identify weaknesses in preparation and require the bank to resolve them. The same review also shows that regulatory approval has limits. Even compliant plans cannot guarantee uninterrupted systemically important services in every crisis, especially for banks with smaller buffers.
The next steps will involve more precise documentation, further crisis exercises and clearer communication arrangements. FINMA’s UBS update later in 2026 will keep pressure on Switzerland’s largest banks, while PostFinance must work through the specific complications created by its role within the postal and payments infrastructure.