payments
Switzerland plans offline card payments for emergencies
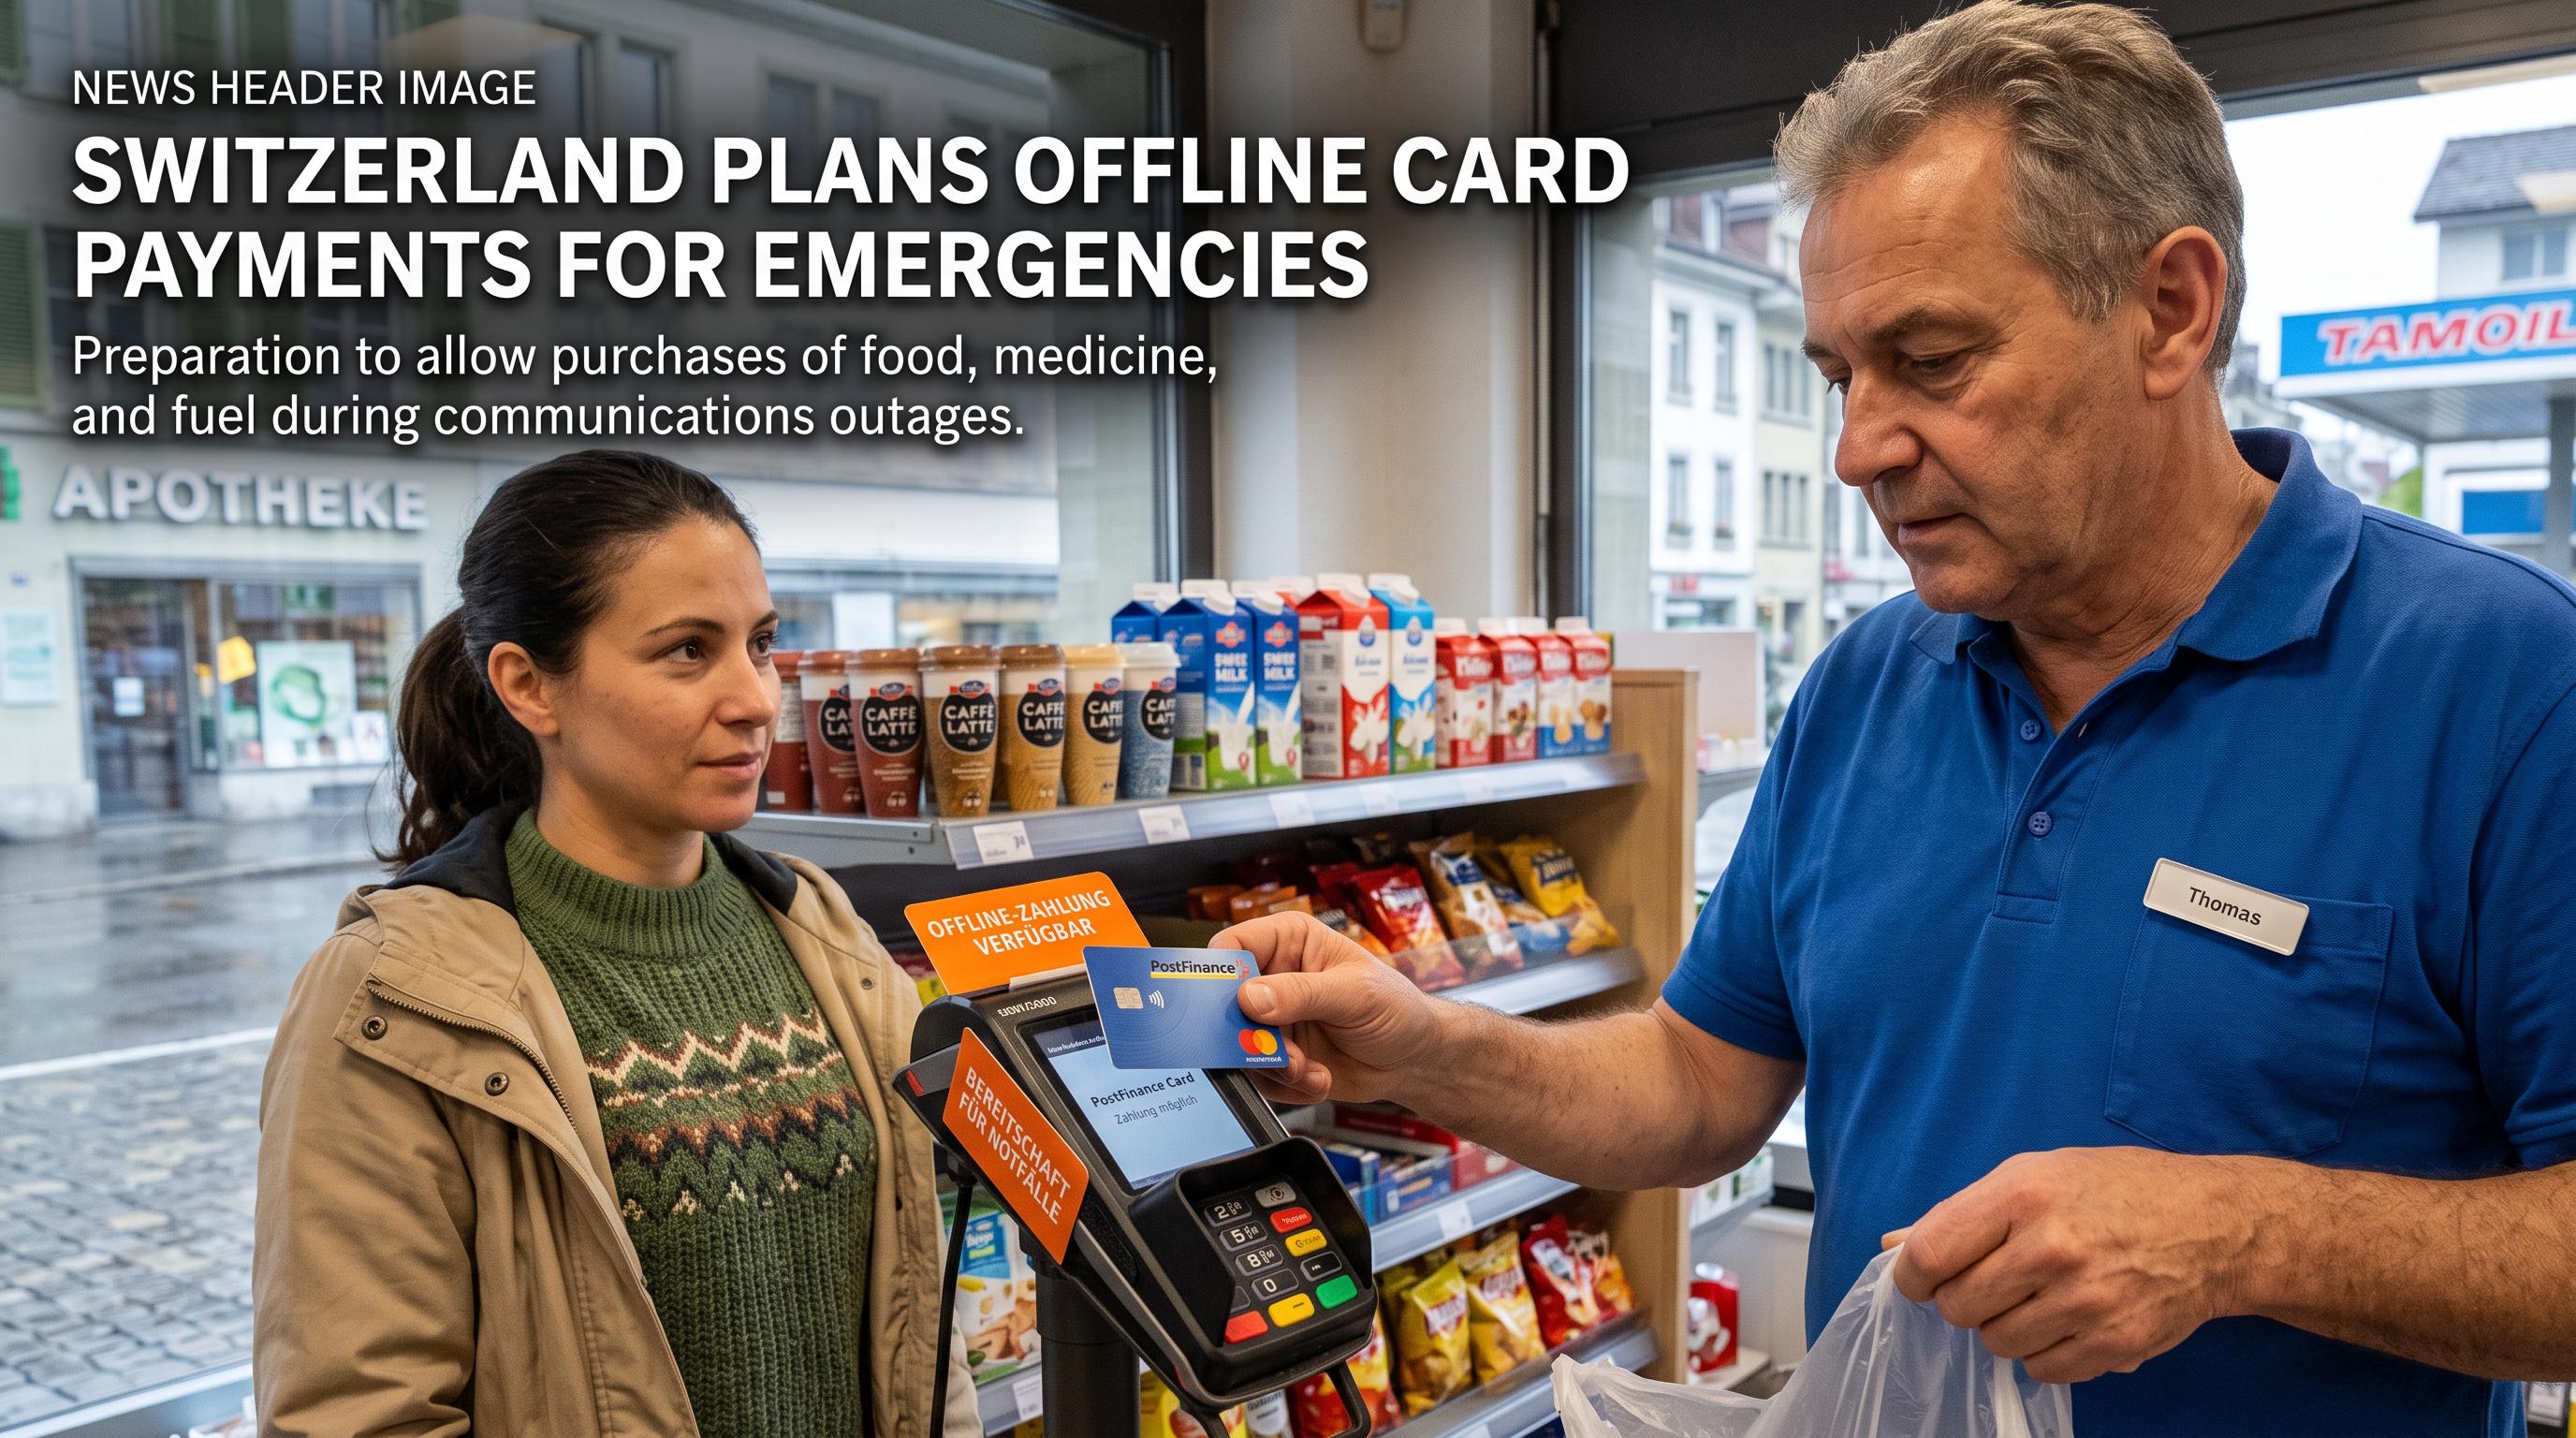
Switzerland is preparing to introduce offline card payments by the end of 2027, allowing purchases of essentials such as food, medicine and fuel during temporary communications outages. Existing physical cards and payment terminals will be used, with PIN verification required.
Switzerland Builds a Payment Backup
By the end of 2027, Swiss shoppers should be able to buy food, medicine and fuel by card during a temporary communications outage. The planned system brings the country’s payment infrastructure into its emergency supply strategy, covering a vulnerability that becomes visible whenever shops lose access to internet or banking links.
The Federal Office for National Economic Supply said disruptions to internet or communications networks can jeopardise the purchase of essential goods. Switzerland relies heavily on electronic transactions, while cash remains an important fallback for households and retailers. The new arrangement will give businesses another option when card terminals cannot reach the payment network.
The initiative involves the Swiss government, banks, payment service providers and retailers. It will use the physical debit and credit cards already in circulation, along with existing payment terminals. Retailers will need to have their equipment reconfigured before the system becomes available.
The plan concerns temporary outages, rather than a permanent replacement for connected payments. It also targets essential goods only. A customer buying groceries, collecting medicine or filling a vehicle could use the system in a disruption, while ordinary purchases outside the designated retail categories would remain outside its scope.
Terminals Store Payments Until Networks Return
The terminal will record the purchase first and transmit it when the connection returns. That delayed processing is the core of the proposed arrangement. During an outage, the payment device stores the transaction locally instead of seeking an immediate authorisation from the bank or payment network.
The customer will still need to enter a PIN. The system is designed for physical debit and credit cards, not a new card product. Mobile wallets and other phone based methods are not identified in the government’s announcement as part of the solution. The source also does not specify how long a terminal may remain offline or how retailers will manage transaction limits and risk controls.
Power remains essential. A payment terminal can operate without an internet connection only if it continues receiving electricity. Shops may rely on the mains supply, a battery or a generator, depending on the disruption. That requirement links payment resilience to the wider reliability of local power systems.
For retailers, the preparation will involve technical reconfiguration and operational planning. Staff will need to know when offline payments are permitted and which goods qualify as essential. The source gives no details on the implementation cost or the precise rules that will govern participating businesses.
Cash Stays in the Emergency Mix
The plan is designed around Switzerland’s dependence on electronic payments while preserving cash as a fallback. When communication links fail, a shop can face a practical problem even if shelves remain stocked and customers have money in their accounts. Connected card payments stop working because the terminal cannot contact the relevant network.
The Federal Office for National Economic Supply described cash as an alternative, while also arguing that people should be able to pay without it. That position reflects the country’s mixed payment culture. Switzerland has advanced digital transactions compared with other countries, according to related Swissinfo reporting, yet many people still regard banknotes and coins as a dependable reserve.
Offline card payments would add a second emergency channel. They could help customers who do not carry enough cash and reduce pressure on retailers during a short disruption. The arrangement may also give essential businesses a clearer role in national preparedness, particularly pharmacies, petrol stations and food retailers.
The system will not remove the need for cash. A terminal still needs electricity, and the planned service will apply only to selected essential retailers. A prolonged outage affecting both communications and power would require other arrangements. The government’s announcement does not state whether retailers will be obliged to participate or how consumers will be informed about eligible shops.
Retailers Face the Implementation Test
The rollout gives Swiss retailers until the end of 2027 to prepare a controlled payment channel for disruptions. The project brings together public authorities, banks, payment providers and businesses, so its success will depend on coordination rather than on a new card issued to consumers.
The source says similar solutions already operate or are being introduced in northern European countries. Switzerland’s timetable therefore places the country within a broader European effort to keep essential commerce running when digital links fail. The announcement does not identify the countries involved or provide performance data from their systems.
Several practical questions remain open. Authorities and providers will need to define which retailers qualify, which products count as essential, and how stored transactions will be protected until transmission. Retailers will also need procedures for outages, staff training and backup power. Customers will need clear instructions, including the requirement to use a physical card and PIN.
For the public, the change should become visible at the checkout rather than in a new wallet or app. Existing cards and readers will support the service once reconfigured. Until the rules and rollout are complete, households should not assume every shop can accept offline payments. The planned deadline is the end of 2027, while the details of the national implementation remain to be published.