Switzerland
Why Switzerland’s federal budget forecasts keep swinging
A sharp upward revision in corporate tax receipts has transformed Switzerland’s projected 2026 federal deficit into a surplus. The story examines why federal forecasts fluctuate so widely and whether the unexpected revenue can be relied upon.
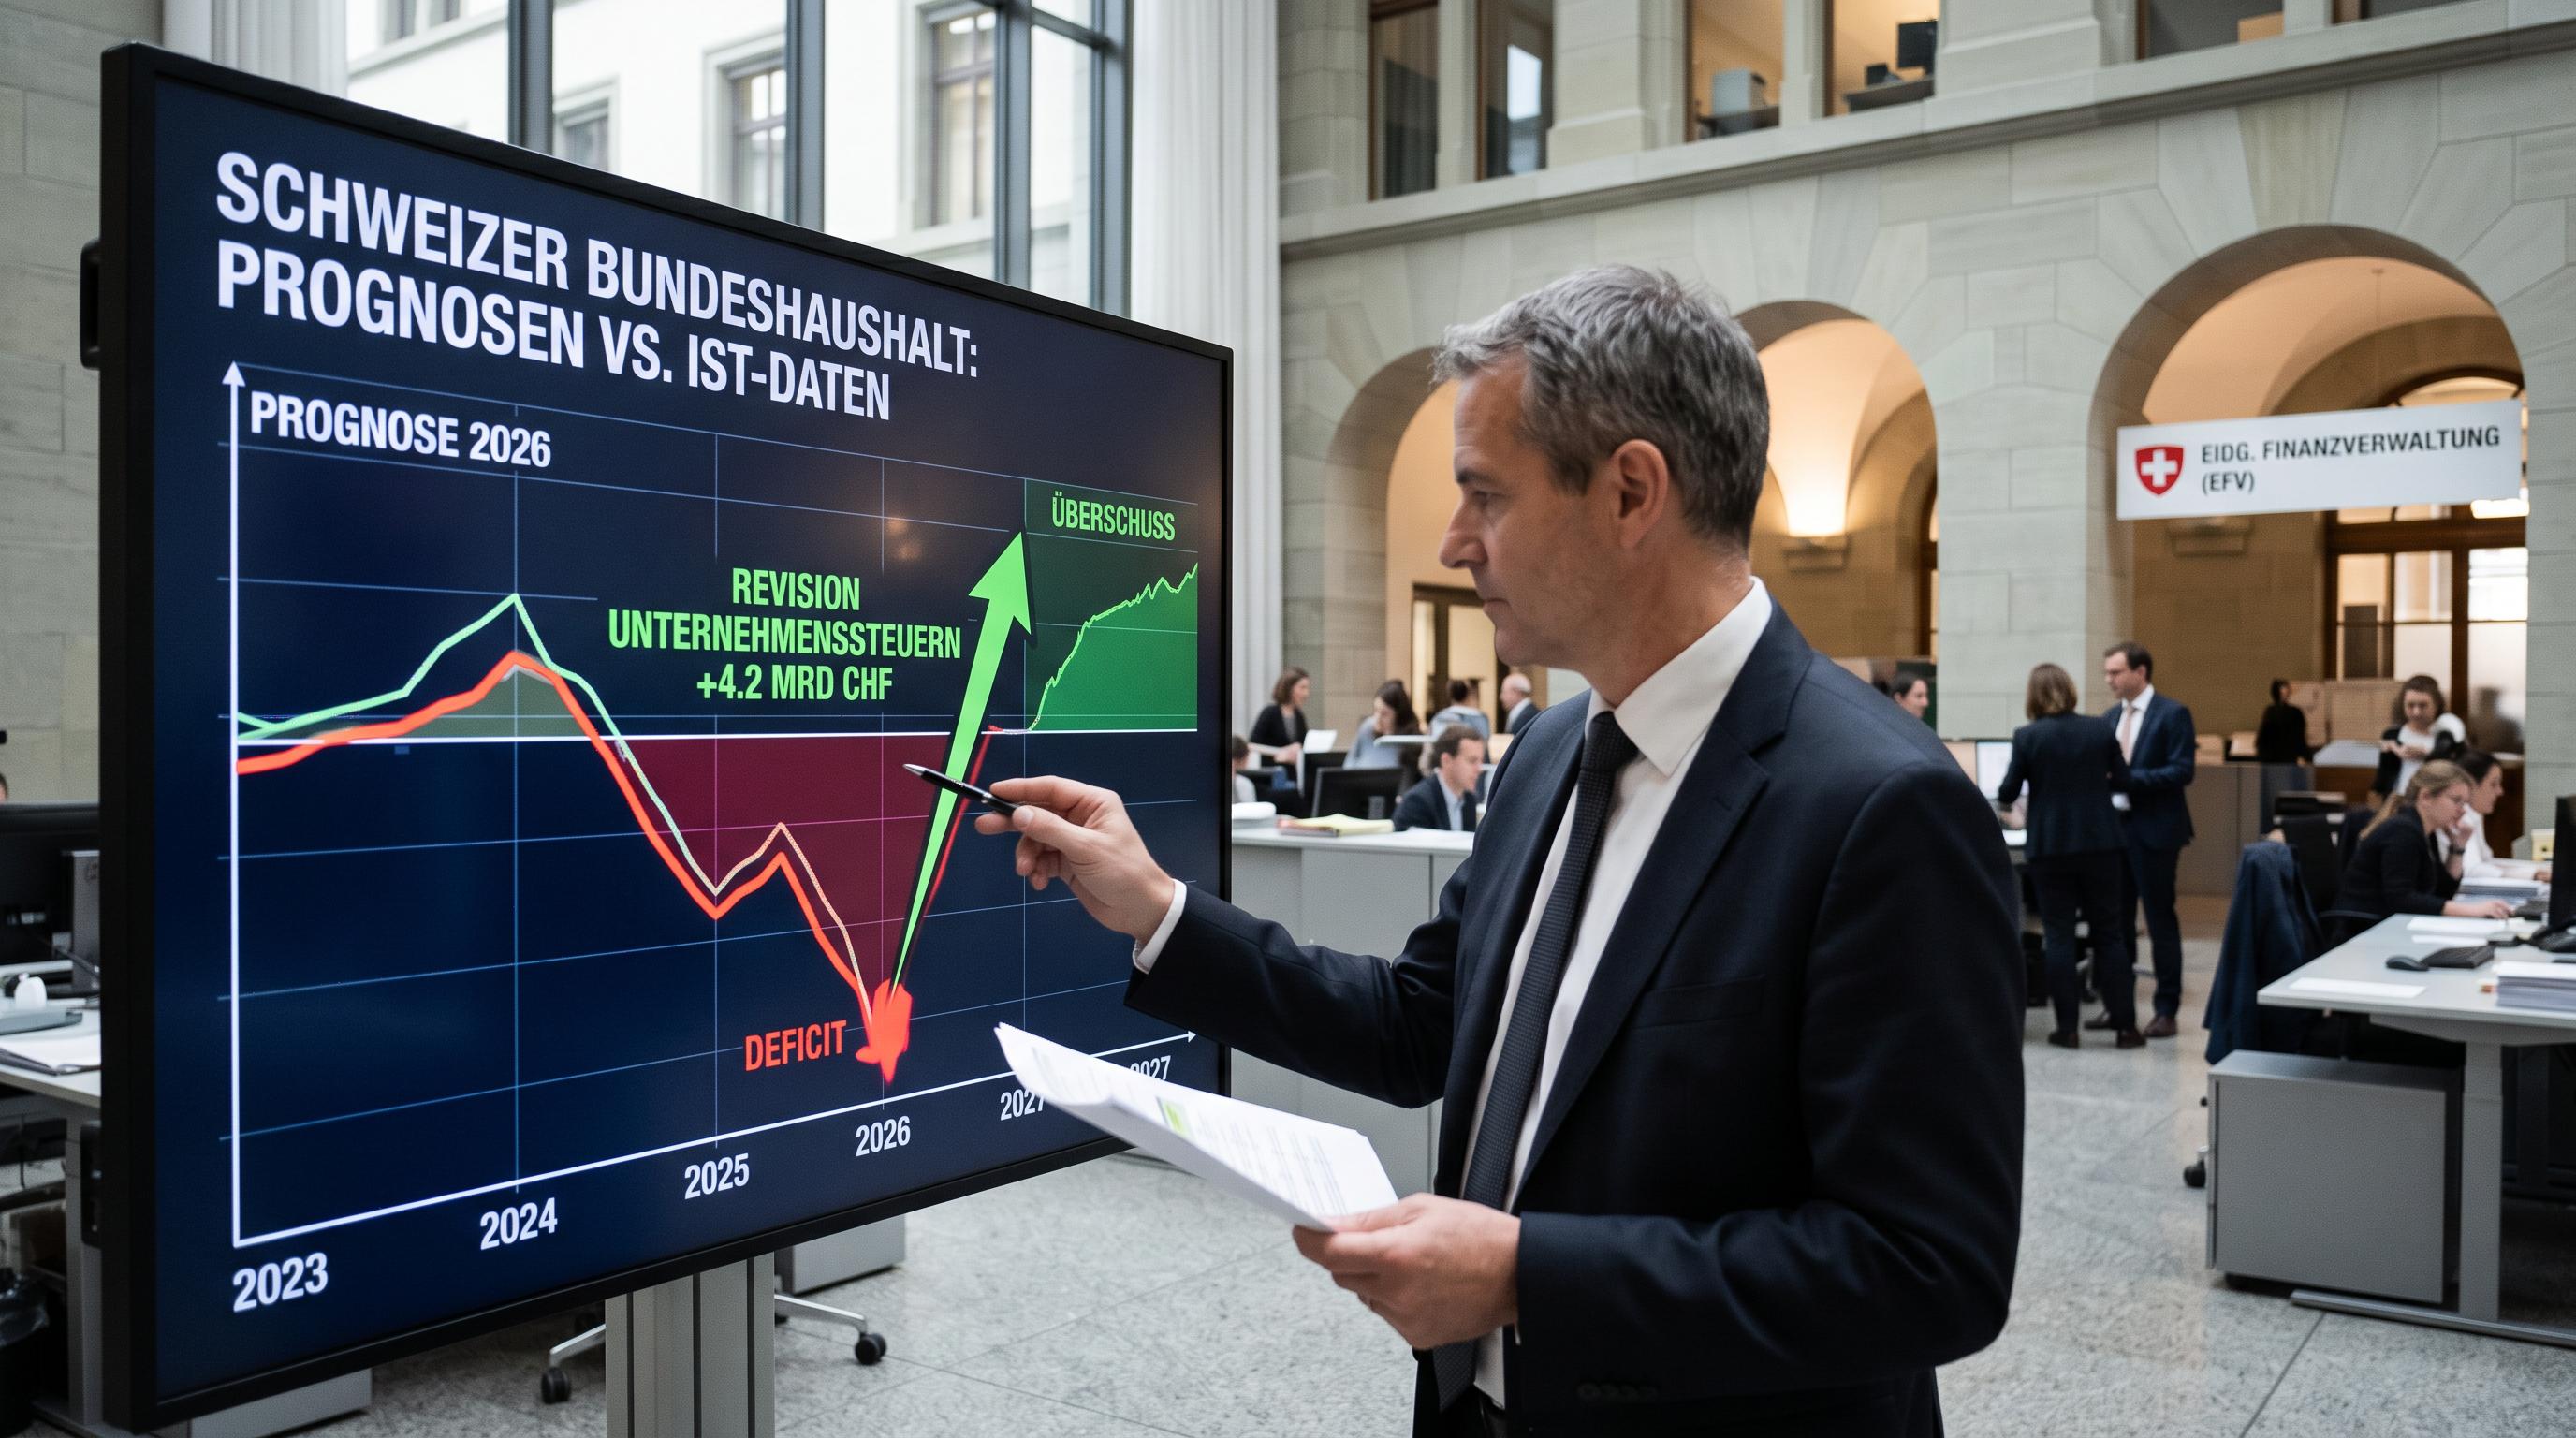
Budget Forecasts Flip Into the Black
A CHF 1.5 billion swing separates the latest deficit and surplus projections. Switzerland’s federal budget outlook has shifted sharply in a matter of months. The finance ministry initially saw a CHF 700 million deficit for the coming budget period. Its revised calculation now points to an CHF 800 million surplus, even after accounting for higher spending, including additional defence costs.
The revision followed a CHF 1.9 billion increase in expected federal revenue announced last month. Corporate taxation supplied most of the improvement. The government now expects federal profit-tax receipts to come in roughly CHF 1.4 billion above the amount included in the 2026 budget forecast.
That change matters beyond the balance sheet. The federal budget sets the room available for defence, social programmes, infrastructure and international commitments. Switzerland’s debt brake also limits how much the Confederation can spend over time, making revenue estimates a significant part of political negotiations in Bern.
The sudden improvement has reopened an old dispute. Left-leaning parties accuse the finance ministry of starting with overly pessimistic assumptions to make spending cuts easier to defend. The ministry rejects that charge and says the latest figures reflect new information about company profits, tax assessments and delayed collections.
A Few Companies Carry the Forecast
Three quarters of corporate tax receipts come from just 0.5% of Swiss companies. That concentration explains why a handful of balance sheets can move the federal outlook by billions of francs.
Switzerland hosts large banks, pharmaceutical groups, commodity traders and multinational companies whose profits can change quickly with exchange rates, energy prices, financing conditions and global demand. When one or two major groups post an exceptional year, the effect reaches the Confederation through the tax system. A weaker year can reverse the movement just as quickly.
The biggest taxpayers are concentrated in a few cantons. Lucerne has attracted companies with a cantonal profit-tax rate of 11.66%. Zurich is home to major banks and other large corporations. Basel City hosts a powerful pharmaceutical industry. Cantonal authorities do not identify the companies behind their corporate-tax totals, limiting the public’s ability to test the federal forecast in real time.
One disclosed example shows the scale involved. MSD, the pharmaceutical multinational headquartered in Lucerne, reported paying CHF 1.8 billion in Swiss taxes in the previous year. A small group of taxpayers of that size can alter national projections even when most Swiss businesses perform normally.
Geneva Adds Windfalls and Delays
Geneva contributed CHF 200 million through retroactive company-tax collections. That money came from taxes that the canton had failed to bill in earlier years, adding another timing problem to an already difficult forecasting exercise.
Geneva has also seen unusually strong results among commodity traders. Companies handling around one third of global oil trading operate from the canton. The war in Iran pushed oil prices and trading profits higher, according to the canton’s comments to Swiss public broadcaster SRF. Higher profits can translate into larger tax bills, although the timing of assessments and payments makes the revenue difficult to place precisely in a single budget year.
These regional patterns give Switzerland’s tax system a distinctive exposure to international markets. A pharmaceutical success in Basel, a bank windfall in Zurich, an exceptional corporate year in Lucerne or a trading boom in Geneva can all feed into the federal accounts. The Confederation receives a share of direct federal profit taxes, while cantons administer much of the underlying information.
Forecasting therefore depends on incomplete early data. Companies file accounts after the budget process begins, tax assessments can be revised, and delayed collections may suddenly appear as current revenue. Those mechanics can create large swings without any deliberate manipulation of the numbers.
Forecasts Become a Political Flashpoint
The finance ministry says its ordinary revenue forecasts missed by an average of only 0.3% between 2016 and 2025. That measure supports the ministry’s argument that large individual revisions do not necessarily prove systematic underestimation.
The historical record still leaves room for political suspicion. In 2018, the ordinary financing balance ended CHF 2.6 billion better than originally budgeted. In 2013, an expected CHF 400 million deficit turned into a CHF 1.3 billion surplus. Such outcomes become politically potent when parliament is debating reductions in federal programmes or restrictions on new spending.
Social Democrat parliamentarian Tamara Funiciello made that argument when the latest revision emerged. She said the Federal Council was “systematically underestimating revenues” to justify cuts and create “new privileges for the wealthiest and large corporations.” The finance ministry denies misleading parliament or the public.
Both sides are responding to the same uncertainty from different positions. Budget planners must avoid committing permanent spending on the basis of temporary revenue. Opposition parties see a risk that cautious forecasts can make austerity appear unavoidable. The reliability of the process depends on whether parliament receives clear explanations for revisions, including the role of late assessments, individual taxpayers and economic conditions.
Separate Windfalls From Lasting Growth
A strong corporate-tax year cannot safely become the foundation for permanent federal spending. Michael Grass of the BAK Economics research institute warned that “individual record years in corporate tax revenue should not readily be interpreted as durable, structural revenue growth.”
That caution will shape the next budget debates. The Confederation can use an unexpected surplus to improve its financing position, absorb higher defence costs or reduce pressure on other spending lines. It should be more cautious about treating the latest CHF 1.4 billion corporate-tax increase as a recurring annual gain. The revenue comes from a narrow base exposed to global markets and the fortunes of a small number of companies.
Swiss taxpayers will also watch how much of the revision survives final assessments. Geneva’s CHF 200 million in retroactive collections cannot be assumed to repeat. Oil-trading profits can fall when prices and geopolitical conditions change. Pharmaceutical and financial earnings move with their own cycles.
The practical test for Bern is transparency. Publishing clearer ranges, identifying the effect of late collections and separating one-off receipts from underlying growth would help parliament judge the spending room. Switzerland’s federal accounts may finish stronger than expected again. The latest figures show why that possibility belongs in the debate, alongside the risk that the windfall will fade.