Housing
Swiss mortgage rates rise at different speeds across regions
Mortgage rates vary sharply across Switzerland, with median ten-year fixed rates in the third quarter ranging from 1. 62% in Central Switzerland to 2. 15% in Valais. The figures highlight how regional conditions are affecting borrowing costs despite a single national currency.
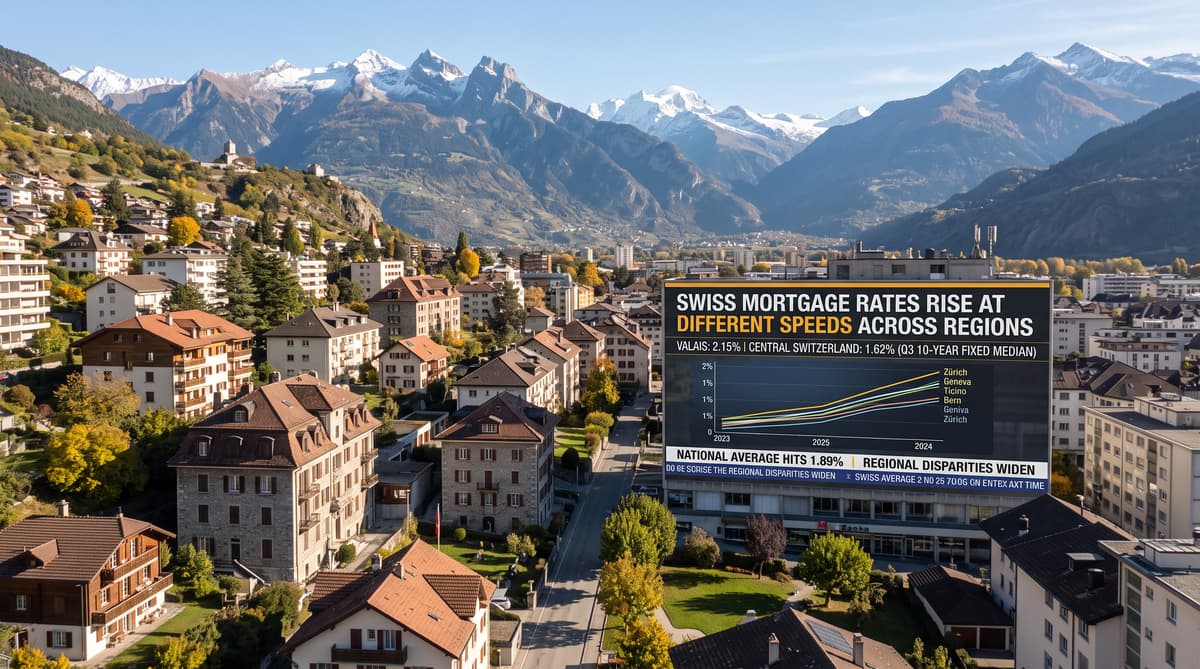
1.84% was the national median for a ten-year fixed mortgage in the third quarter of 2026, up 14 basis points from the previous quarter. The rise has reached households across Switzerland, yet the bill attached to a new loan depends heavily on the canton and the lender competing for the business.
Resolve's quarterly mortgage report places the widest regional gap between Central Switzerland, where the median ten-year rate stood at 1.62%, and Valais, at 2.15%. Zurich followed closely behind Central Switzerland at 1.65%. Geneva recorded 1.78%, while Neuchâtel reached 1.90%.
The movement reflects a national funding market under pressure. The swap rate used to price fixed mortgages increased by 19 basis points during the quarter. Lenders absorbed part of that increase by accepting narrower margins, particularly where they faced strong competition.
For borrowers, the figures make location and timing financially significant. A mortgage offer negotiated in one part of Switzerland cannot be treated as a reliable guide to the price available elsewhere. The same national currency and monetary system leave room for markedly different local borrowing costs.
Make Competition Work for Borrowers
German-speaking Switzerland saw increases of only 5 to 7 basis points, compared with 10 to 13 basis points in French-speaking Switzerland. The difference points to the structure of local banking markets, where the number and type of competing lenders can determine how much higher funding costs reach borrowers.
German-speaking Switzerland has a dense field of providers. Cantonal banks increasingly operate beyond their home territories, while cooperative banks, regional institutions and pension funds also compete for mortgage business. That gives borrowers more opportunities to compare offers and gives lenders a reason to protect market share through tighter margins.
Competition is thinner in French-speaking Switzerland. Cantonal banks there generally remain closer to home, limiting the number of institutions actively chasing the same customer. Geneva's median rate was 1.78%, compared with 1.65% in Zurich, a gap of 13 basis points.
Ticino recorded the sharpest quarterly increase, at 15 basis points. The report links the move to a market with fewer competing lenders. Local market power therefore remains a practical part of the mortgage price, even as banks respond to the same national funding signals.
Compare Offers Before Signing
The best and least competitive ten-year offers diverged by 98 basis points in the third quarter, up from 80 basis points in the second. The spread gives borrowers a larger financial reason to shop around, especially when refinancing a large loan or fixing a rate for a decade.
For a mortgage of CHF 900,000, the difference amounts to approximately CHF 8,820 in annual interest. That calculation illustrates the scale of negotiation without implying that every borrower can access the cheapest advertised offer. Banks may condition discounts on several factors, including transferring daily banking, moving pension assets, contributing more equity or financing an energy-efficient property.
Some institutions have held rates below their preferred margin to win market share or reach lending targets before the end of the year. Others have faced less pressure to follow. National lenders seeking growth can undercut local banks, while pension funds often compete selectively. Most insurers remain largely outside the contest.
Borrowers comparing offers should therefore examine the full package, including conditions, flexibility and ancillary products. A lower headline rate can carry requirements that change the total value of the deal.
Read Regional Medians in Context
Valais's 2.15% median rate needs careful interpretation because the canton has a high share of second homes. Holiday properties can attract a risk premium, so the figure does not represent the likely rate for every owner-occupied main residence in the canton.
Mortgage medians also combine borrowers and properties with different risk profiles. A lender may offer one price to a household with substantial equity and another to a buyer financing a less energy-efficient property. Income stability, pension assets, banking relationships and the intended use of the property can all affect the final offer.
The regional data remain useful because they reveal how local market conditions shape pricing. They become misleading when treated as a simple league table of lenders or cantons. A high median can reflect the mix of loans being written, just as a low median can reflect aggressive competition for selected customers.
That distinction matters particularly in tourist regions, where second-home financing and seasonal property markets sit alongside ordinary residential borrowing. Prospective buyers should ask lenders how the quoted rate reflects occupancy, property type, loan-to-value ratio and additional banking commitments.
Track Benchmarks Before Renewal
The underlying swap rate rose 19 basis points, while the national mortgage median rose 14 basis points. The five-basis-point difference shows that lenders did not pass the full increase in funding costs through to customers during the quarter.
Expectations of tighter monetary policy, including a possible Swiss National Bank rate increase before the end of 2026, pushed the benchmark higher. Fixed mortgage pricing responds to market expectations as well as current official rates, so borrowers can see offers move before a policy decision arrives.
Local competition will determine how much of any further increase reaches households. German-speaking markets have more institutions able to defend or capture business. French-speaking cantons and Ticino may offer fewer alternatives, although individual lenders can still compete aggressively for selected customers. Pension funds and national banks add another layer to the market when their lending criteria fit a borrower's profile.
Switzerland's mortgage market will therefore continue to combine national funding pressure with regional pricing. Borrowers approaching a renewal date have a clear practical task: begin early, request multiple offers and check the conditions behind each rate. The spread between lenders can matter as much as the next move in the benchmark.