watchmaking
Luxury boom masks a widening divide in Switzerland’s watch industry
Swiss watch exports have stabilised, but the apparent recovery is being driven by a small luxury segment while many manufacturers face weaker demand, tariffs, high gold prices and a strong franc. The story should examine the widening divide between elite brands and the rest of the industry.
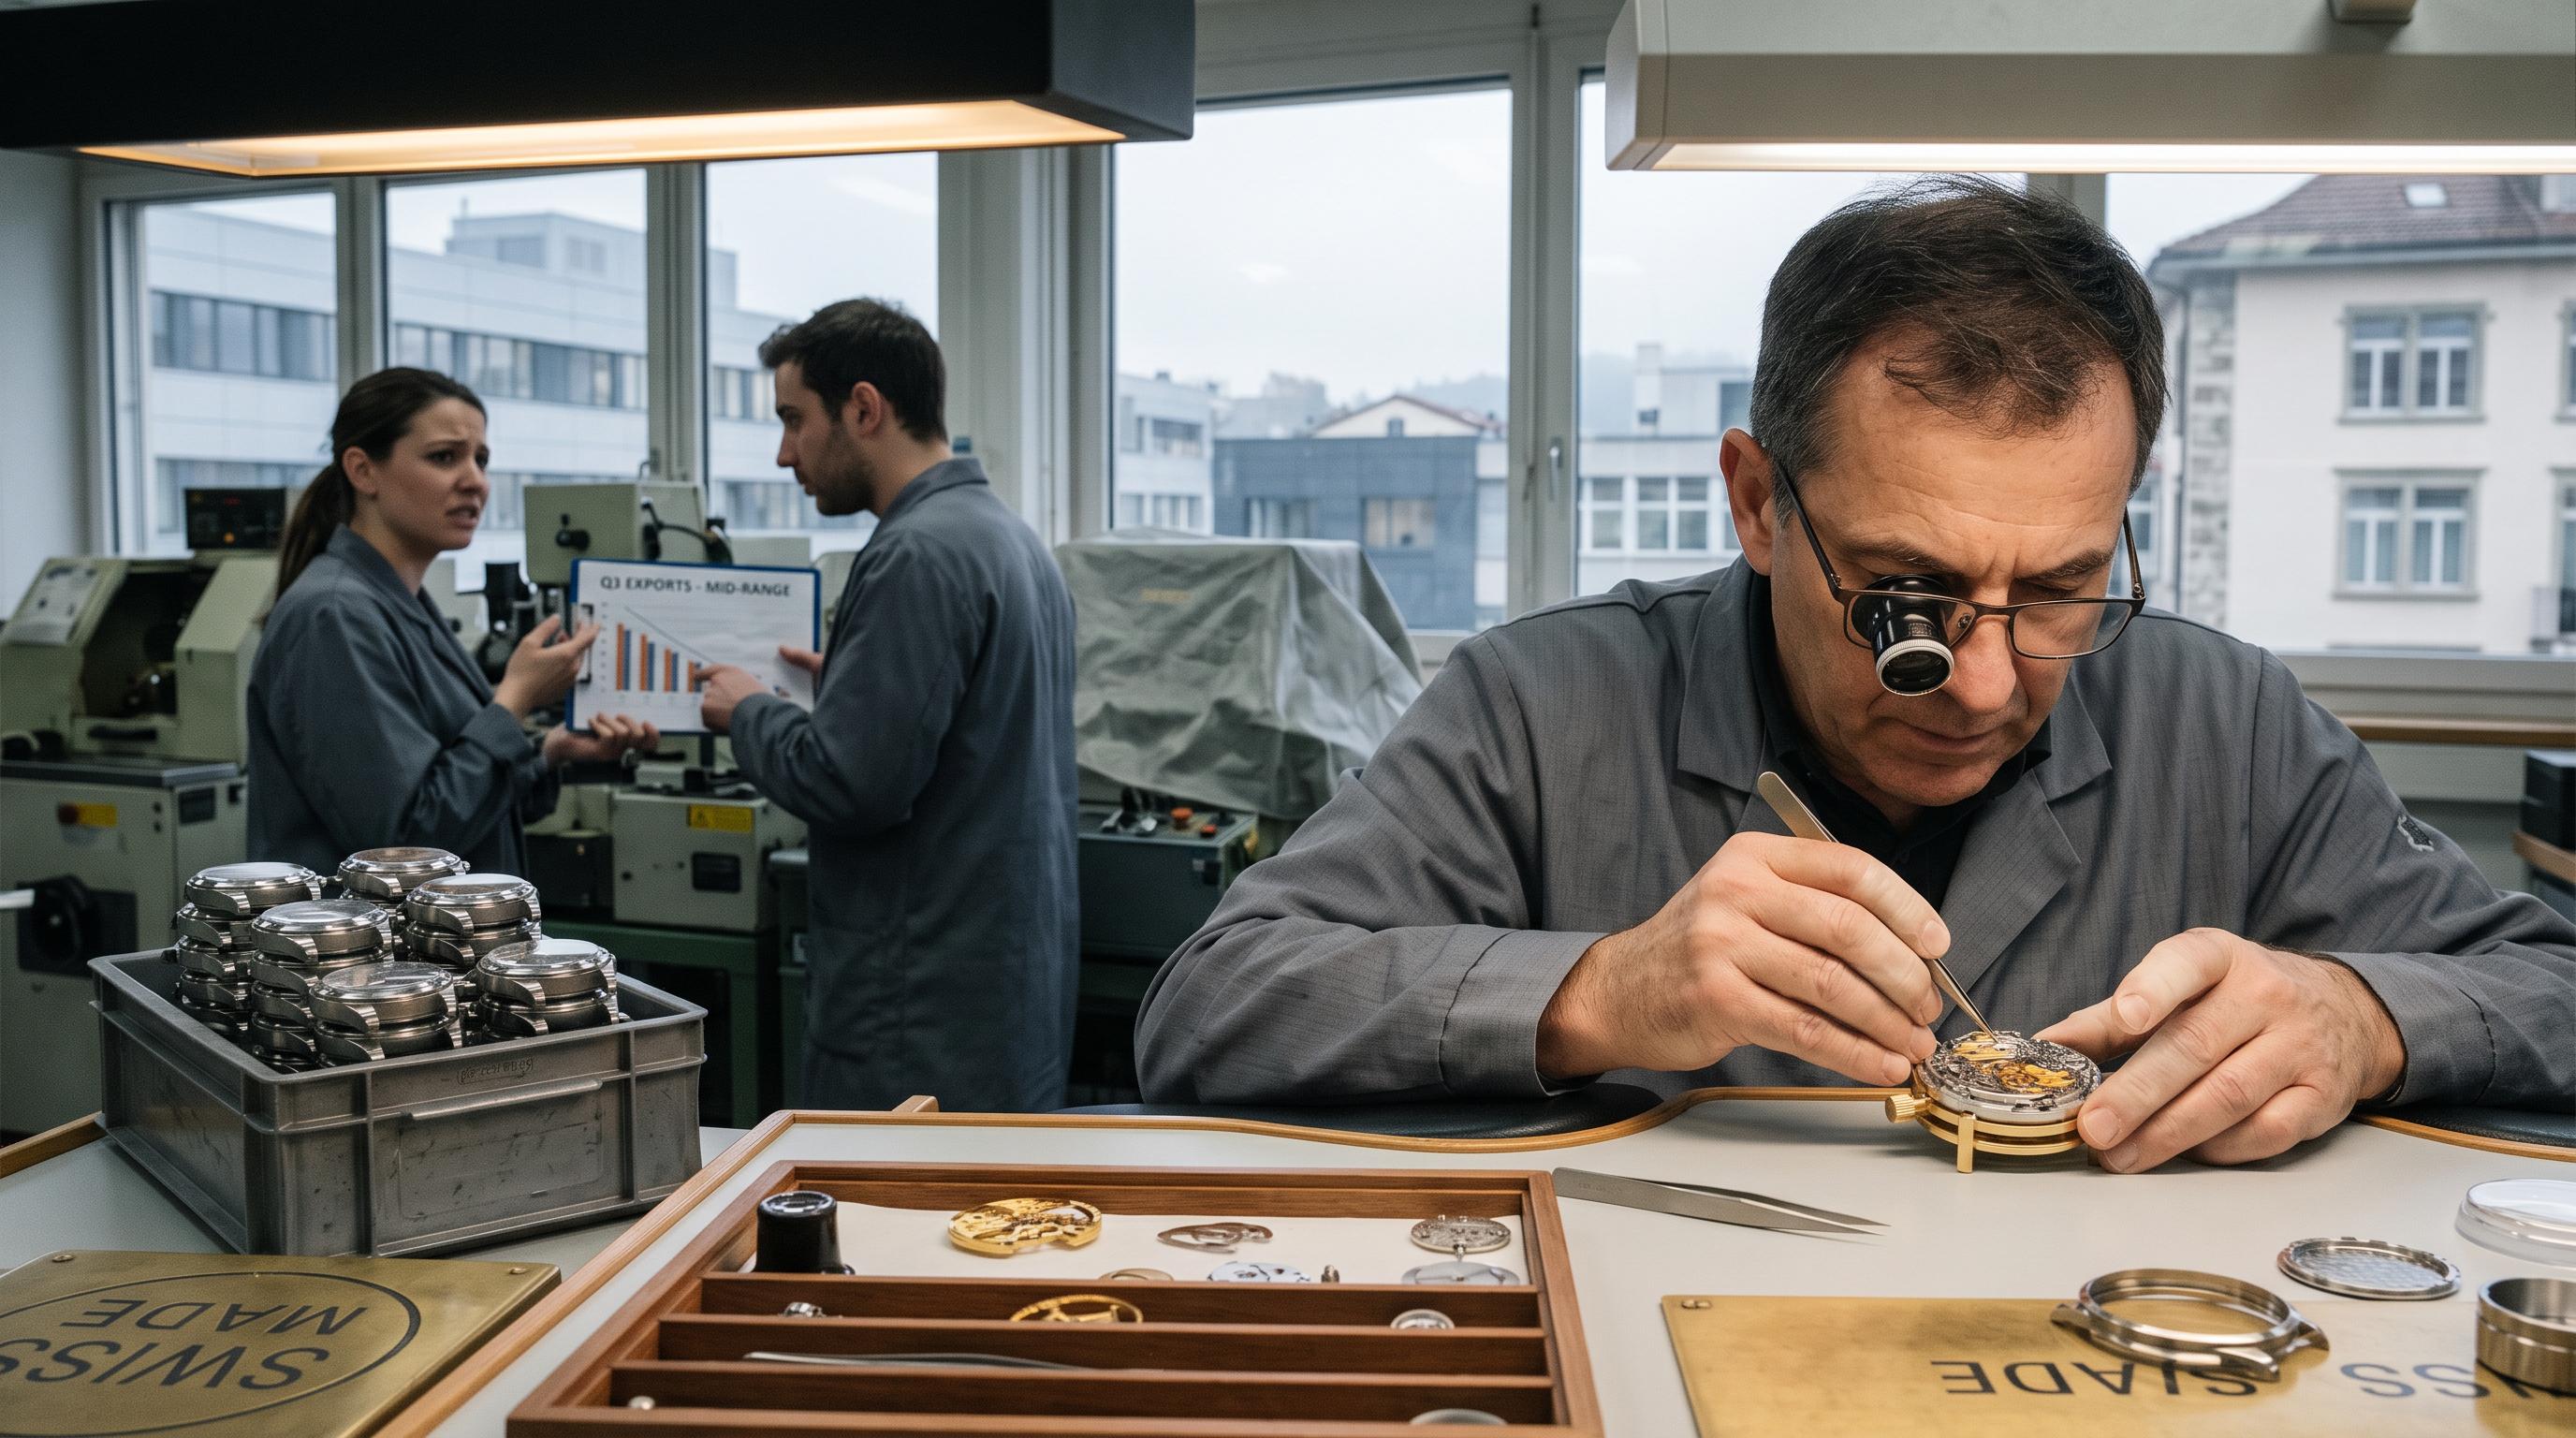
Exports Stabilise, But the Recovery Splits in Two
CHF 12.2 billion in exports has not delivered a broad recovery. Swiss watch exports stabilised in the first half of 2026, with value down just 0.6% from a year earlier and volumes up 2.3%. Behind those figures, manufacturers across the sector are experiencing sharply different conditions.
A small group of ultra luxury watches is supplying most of the industry's value growth. LuxeConsult, using data from the Federation of the Swiss Watch Industry, found that watches representing only 1.3% of volumes accounted for 75% of market value growth. The result is a recovery visible in export totals, but uneven on factory floors and in retailers' inventory rooms.
The industry has spent three years absorbing wars, tariffs, a strong Swiss franc, expensive gold and weaker demand for luxury goods. The pressure has encouraged brands and suppliers to use Switzerland's RHT short time work scheme to preserve jobs and specialised skills. Yves Bugmann, president of the industry federation, said uncertainty remained high and expressed hope that conditions would improve in the coming months.
For Switzerland's watchmaking regions, the distinction matters. Export value can hold steady while production schedules, supplier orders and household incomes remain under pressure.
Ultra Luxury Carries the Market
The top 1.3% of watch volumes generated 75% of value growth. That concentration defines the industry's current economics. Ultra luxury pieces are carrying export performance even as larger parts of the market struggle to move stock.
Oliver Müller, founder of LuxeConsult and author of the report, said the growth of ultra luxury was spectacular and showed the direction of the wider market. The gains reflect the spending power that remains among wealthy customers, even after the broader luxury market weakened. They also show why headline export values can give an incomplete picture of demand.
The squeeze is particularly clear in the CHF 25,000 to CHF 50,000 bracket. Sales in that segment fell 8.3%, making it the weakest performer identified in the report. Retailers have become more cautious about replenishing inventory, according to Müller. Brands cannot assume that expensive watches will automatically sell through once they reach a shop window.
Accessible luxury performed better, but only marginally. Watches priced from CHF 7,500 to CHF 12,500 rose 0.5%, helped by steel models from Rolex, Omega and Cartier. That modest increase suggests that buyers remain selective. Reputation, design and resale confidence are carrying more weight as retailers and customers reduce their exposure to slower stock.
Volume Brands Keep Swiss Skills Alive
Swiss watch exports fell from 17 million units in 2023 to 14.6 million in 2025. The first half of 2026 brought a modest volume rebound, driven largely by Longines, Tissot, Hamilton and Swatch, all brands owned by Swatch Group.
Those brands occupy a different commercial terrain from the ultra luxury houses. Their watches bring production scale, broad retail distribution and a stronger connection to everyday consumers. The volume increase offers some relief to factories and suppliers, but it does not erase the decline of the previous two years or the weakness affecting other manufacturers.
Gold prices have raised input costs, while the strong franc makes Swiss production more expensive for overseas buyers. Tariffs add another layer of uncertainty. Companies must decide how much to produce before they know whether retailers will reorder, and smaller suppliers have less room to absorb delayed payments or reduced contracts.
Many firms have turned to RHT, Switzerland's short working hours programme, to retain workers and protect expertise. That support can preserve capacity during a downturn, but it also signals that the recovery has not reached the full industrial network. A factory may remain open while operating well below its previous rhythm.
New Brands Target Retailer Fatigue
New names are entering the market while established brands fight for share. House of Brands revived Gallet after a hiatus dating back to the 1980s, following the reintroduction of Universal Genève. Former Audemars Piguet chief executive François Henri Bennahmias announced N3W5 in July, with its first watches due next autumn. Niton, another dormant dial name, was revived earlier this year by former Girard Perregaux executive Leopoldo Celi.
The launches reflect a market where novelty can matter as much as heritage. Bennahmias argues that consumers have money but are tired of seeing the same products. Georges Kern, chief executive of House of Brands, said retailers do not want a twentieth version of an existing design and welcomed new options for their shelves.
Gallet plans to sell watches priced between £2,220 and £5,300, a gateway to luxury that sits below the most expensive Swiss pieces. Kern says there is still business at that price point, although winning it requires brands to take share from competitors.
That strategy carries risk. New labels must finance product development, marketing and distribution while retailers limit inventory. Yet the return of dormant names shows that investors and executives still see room for differentiation, especially where established collections have become repetitive.
Switzerland Faces an Uneven Watchmaking Future
The next phase will be measured in jobs, orders and repeat purchases, not export value alone. Switzerland's watch industry remains a major industrial and cultural asset, concentrated across cantons including Neuchâtel, Bern, Jura, Geneva and Vaud. Its resilience depends on the suppliers, technicians and assemblers who support brands at every price level.
The current figures offer mixed signals. Export volumes have started to rise, but annual unit shipments remain well below their 2023 level. Ultra luxury is expanding its share of value, while the CHF 25,000 to CHF 50,000 segment is contracting and accessible luxury is barely growing. The result leaves mid market manufacturers exposed to weak retail traffic and cautious purchasing.
Brands will need to manage production more closely, refresh designs and give retailers stronger reasons to commit capital. Suppliers will face similar pressure as orders become less predictable. State support can protect skills during the adjustment, but it cannot create lasting demand.
For Swiss watchmaking, the test is whether elite growth can coexist with a healthy manufacturing base. The answer will emerge gradually, through factory utilisation, retailer replenishment and the ability of brands to persuade customers that the next watch offers something beyond a familiar name.