Swiss National Bank
Why Switzerland is keeping interest rates at zero
Switzerland’s zero-percent policy rate stands out as other major central banks consider tighter policy. The article should explain why the Swiss National Bank has kept rates so low, how inflation and the franc shape its choices, and who benefits or loses from cheap borrowing and weak savings returns ahead of the September 24 decision.
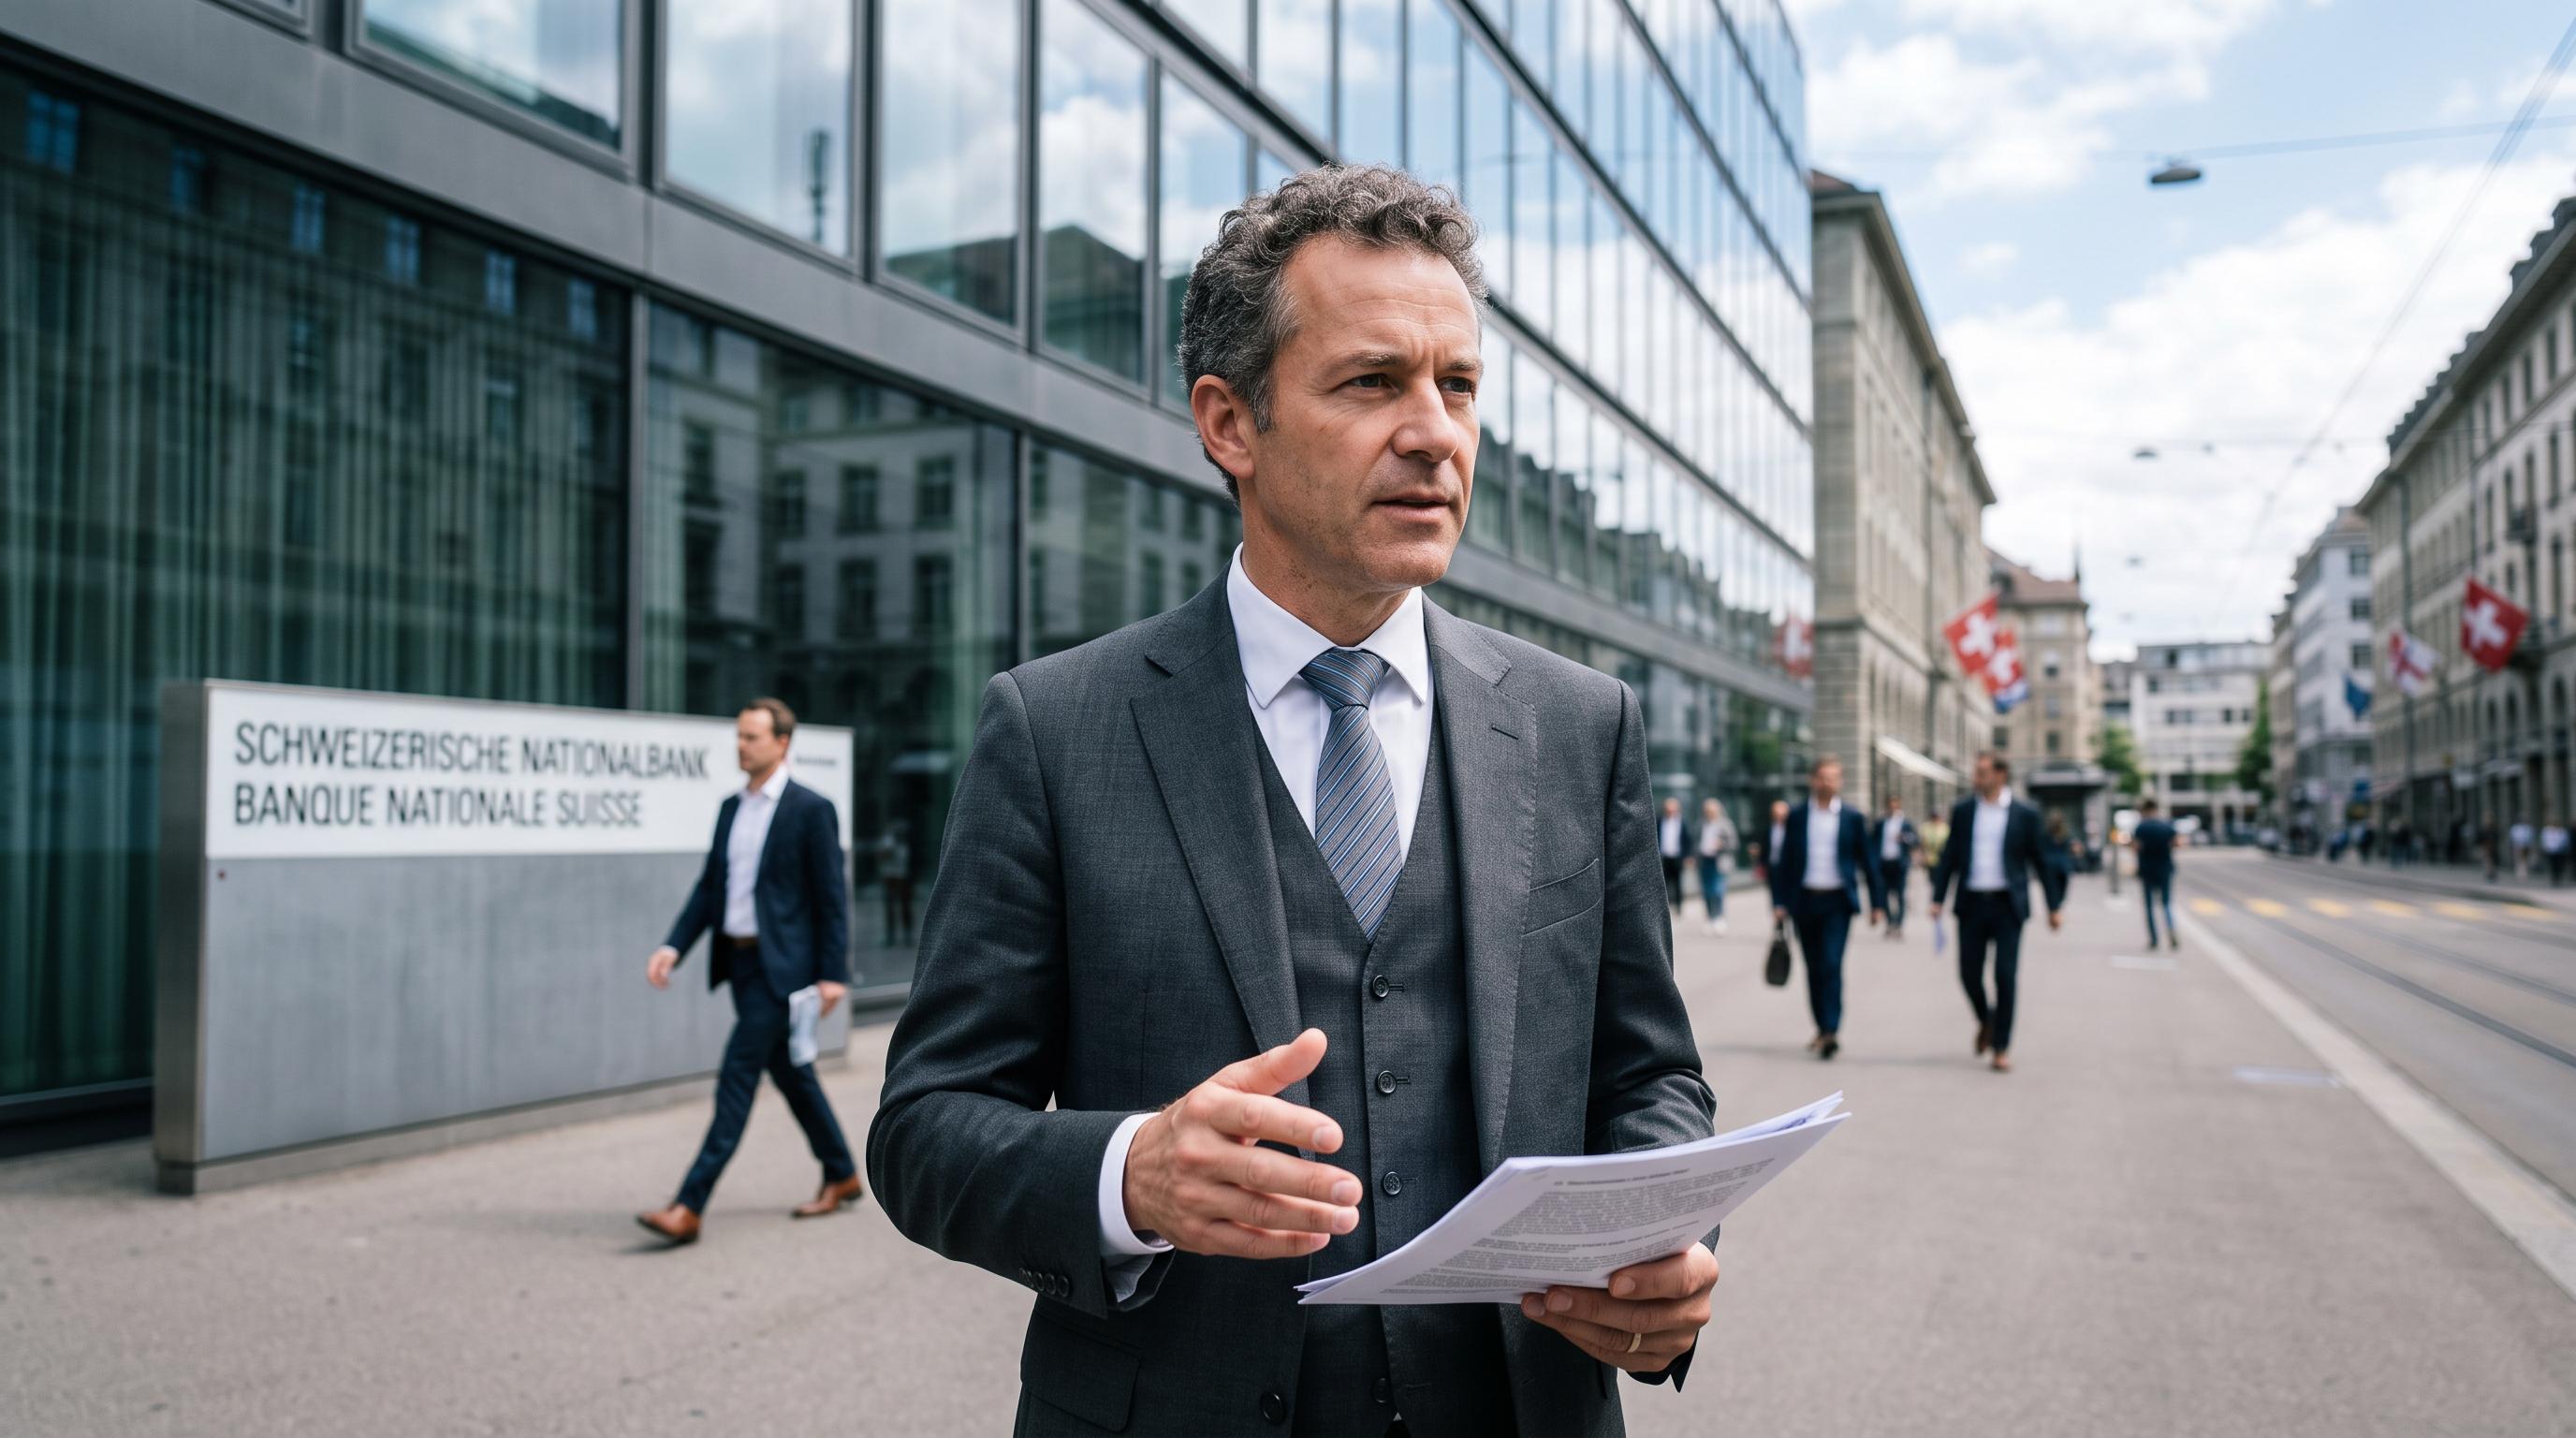
The SNB Holds the Line at Zero
The SNB is holding its policy rate at 0% while the rest of the major central-bank world sits materially higher. The decision matters for every Swiss household with a mortgage, savings account or pension portfolio, and the next test arrives on September 24, 2026.
The European Central Bank has set its rate at 2.25%, while the US Federal Reserve range stands at 3.5% to 3.75%. Switzerland's rate has remained at zero for more than a year. That gap has made the country a monetary outlier, though not an isolated one. The SNB is responding to domestic conditions rather than matching Frankfurt or Washington step for step.
Swiss inflation reached only 0.8% in August. The figure compares with an average of 2.9% across European countries in July and 3.4% in the United States. Those numbers reduce the immediate need for the SNB to restrain demand through more expensive credit.
The policy has practical effects. Borrowers can still access relatively cheap financing, while savers receive little or no return on ordinary bank deposits. The same rate that supports households and companies also compresses income for people relying on cash savings. The September decision will show whether the SNB believes that balance has changed.
Low Inflation Gives Bern Breathing Room
Switzerland's low inflation gives the central bank room to wait. Caroline Hilb, head of investment and pension provision at Raiffeisen Bank, links the policy to two longstanding features of the Swiss economy: contained price growth and a strong franc.
A stronger currency makes imported goods and raw materials cheaper in Swiss franc terms. That can help restrain consumer prices, particularly in an economy that buys substantial amounts from abroad. It also means the SNB does not face the same inflation pressure confronting larger economies. Hilb said that Swiss inflationary pressure remains too low to require a rate adjustment.
Public finances reinforce the country's resilience. Switzerland's debt brake limits the government's ability to run persistent deficits and requires spending to balance with income over the economic cycle. In boom periods, surplus revenue can be used to reduce debt, creating room for weaker economic years. UBS chief economist Daniel Kalt said the system helps prevent the state from spending taxpayers' money recklessly.
That fiscal record does not dictate monetary policy, and it cannot shield Switzerland from international shocks. It does, however, reduce one source of pressure on domestic rates. With low inflation, limited public debt and a stable currency, the SNB can keep its focus on Swiss demand rather than importing the rate path of the ECB or the Federal Reserve.
The Franc Holds Down Imported Inflation
The franc remains the SNB's quiet inflation-fighting tool. A stable or strong Swiss franc limits the cost of imported energy, food and manufactured goods. That effect helps explain why Switzerland can maintain a zero policy rate while the United States and eurozone operate well above it.
The currency also complicates any move higher. If the SNB raised rates while other conditions stayed unchanged, Swiss assets could become more attractive and the franc could strengthen further. That would ease imported inflation, but it could make Swiss exports more expensive for customers abroad. Manufacturers, tourism businesses and companies with revenue in euros or dollars would feel the exchange-rate pressure through their pricing and earnings.
The source does not suggest that the franc is completely insulated from international markets. Hilb noted that Swiss interest rates have risen alongside global rates, although the increase has been significantly weaker than in other European countries and the United States. “Interest rates are part of an international landscape,” she said.
This is why the SNB watches the currency even when domestic inflation looks calm. A weaker franc could raise import costs and add to price pressure. A stronger franc could hurt exporters and deepen the challenge for companies competing overseas. The central bank must weigh both effects before changing a rate that currently stands at zero.
Borrowers Keep the Advantage
Cheap credit continues to support borrowers, with average 10-year mortgages at 1.9%. Swiss households carrying home loans benefit when financing costs remain low, and businesses can invest or refinance at a lower price than they would face under a tighter policy regime.
The benefit is especially visible in a property market where homes are expensive and household debt is substantial. A low rate can reduce monthly payments and make a fixed mortgage easier to service. It can also support demand for housing, which may keep prices firm in areas where supply is limited. Borrowers who locked in longer-term financing still face refinancing risk when their contracts expire, particularly if global rates remain elevated.
The effect is not uniform across Switzerland. A homeowner with a mortgage gains from cheap financing, while a renter may see no direct reduction in housing costs. A small company with debt can preserve cash for wages or equipment, while a firm dependent on savings income receives little compensation for its reserves.
International rates still reach Switzerland through financial markets. Hilb said Swiss mortgage rates had risen slightly even as the SNB kept its policy rate at zero. Comparis put the average 10-year mortgage at 1.9%, showing that the policy rate is not the same as the rate households pay for every loan.
Savers Wait for a Better Return
Savers pay the clearest price for a zero-rate economy. Money held in ordinary bank accounts earns little or no interest, leaving households with fewer ways to preserve purchasing power through cash alone. Retirees, cautious savers and people building emergency funds feel that pressure most directly.
Pension funds and other long-term investors also operate in a difficult low-yield environment. They must seek returns across bonds, equities, property and other assets, while managing the risks that come with those choices. The source does not quantify the impact on individual pension outcomes, but the direction is clear: low benchmark rates reduce the income available from conservative investments.
The policy creates other trade-offs. Cheap money can support housing demand and encourage borrowing, while a strong franc can help contain prices but weigh on exporters. A decision to raise rates could improve returns for savers and cool credit demand. It could also increase mortgage costs, strengthen the franc and place more pressure on companies selling abroad.
Daniel Kalt said Switzerland is not under pressure to raise rates because inflation remains too low. Caroline Hilb likewise sees no current need for an adjustment because inflationary pressure is limited and the franc is stable. The SNB's September 24 decision will therefore turn on whether those conditions still hold, not on the higher rates set elsewhere.