payments
Offline card payments planned for Swiss shops by 2027
Switzerland is preparing to introduce offline card payments for essential goods by the end of 2027. Physical debit and credit cards could be used during temporary communications outages, with transactions recorded and processed once connectivity returns.
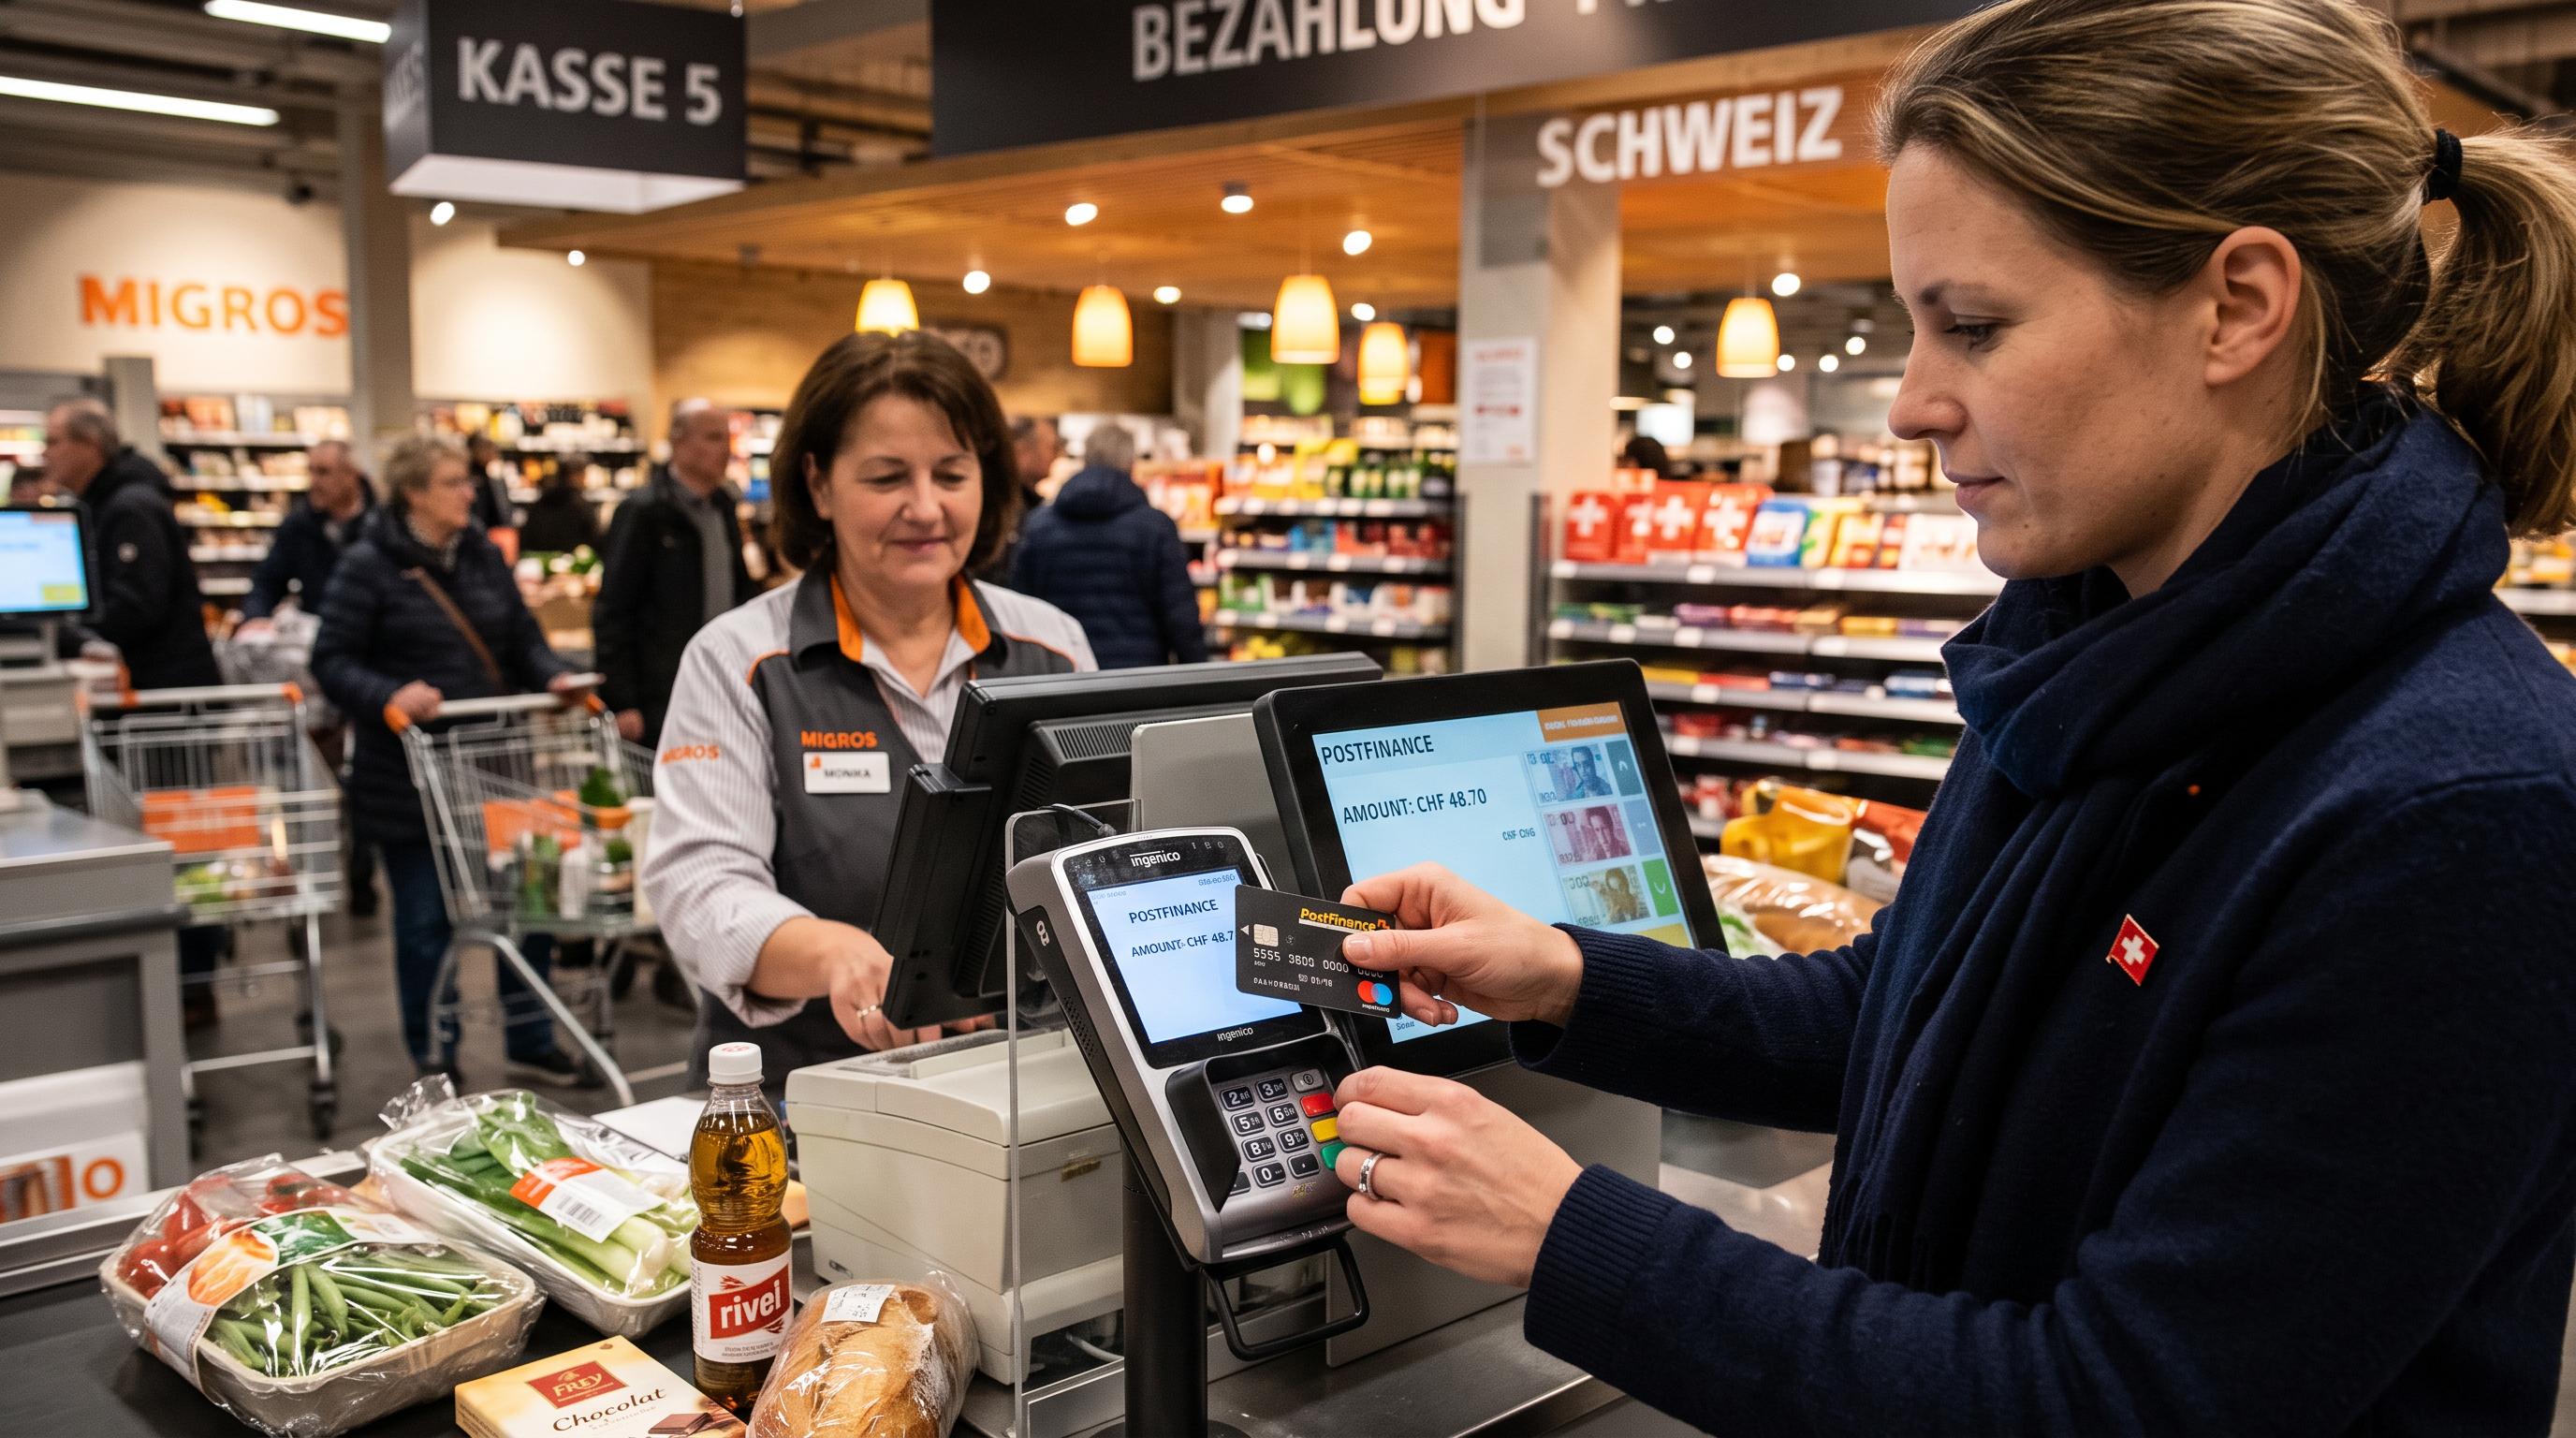
Switzerland Draws a Line Against Payment Blackouts
Switzerland is putting a deadline on payment resilience: by the end of 2027, essential retailers are expected to accept physical debit and credit cards even when communications links fail.
The plan brings the country’s banks, payment providers, retailers and government around one urgent objective: keep food, medicines and fuel moving when the digital networks that normally authorise a purchase suddenly go dark.
At present, a temporary internet or communications outage can turn a routine card payment into a barrier at the checkout. Cash remains the immediate fallback, but the Federal Office for National Economic Supply argues that Switzerland must also preserve the ability to pay electronically without a live connection. That matters in a country where daily commerce increasingly depends on card transactions, even as cash retains its reputation as a dependable safe haven.
The proposed system does not promise business as usual everywhere. It targets shops selling essential goods, not every retailer on every high street. Yet its significance is broader than the checkout queue: a payment network that can withstand a communications interruption strengthens the country’s wider supply security. Switzerland is now preparing for the moment when connectivity fails—and commerce cannot afford to stop.
The Terminal Records Now—and Settles Later
The key change is simple but consequential: the terminal records the purchase first and sends it later.
Under the planned arrangement, a card reader can store an offline transaction during a temporary loss of internet or communications connectivity. Once the link returns, the device transmits the payment and the customer’s account is debited at a later stage. The checkout no longer has to wait for an immediate connection to complete the sale.
That delay changes the rhythm of payment, but not the basic act of buying. Customers will use an existing physical debit or credit card and enter a PIN. The source specifically says no new payment cards are needed. Instead, retailers will have to reconfigure their existing card readers so they can support the offline process.
The design also exposes a crucial limit. A disconnected terminal is not a magic solution if it has no power. The reader must continue operating from the mains, a battery or a generator. In other words, Switzerland’s offline-payment strategy depends on two forms of resilience at once: communications must be able to fail while the checkout remains powered. That combination will determine whether the policy works under real pressure.
Food, Medicine and Fuel Get First Priority
The protection is deliberately narrow: offline card payments are reserved for the goods people cannot safely do without.
Supermarkets, pharmacies and petrol stations sit at the centre of the plan because a communications outage can quickly become a supply problem. Food purchases cannot simply be postponed indefinitely. Medicines may be time-sensitive. Fuel supports mobility and, in some emergencies, the generators and vehicles that keep essential services running.
That targeted approach also draws a hard boundary. The reported system is intended exclusively for retailers selling essential goods. It is not presented as a universal replacement for online authorisation, and the source does not say that restaurants, boutiques or other non-essential businesses will receive the same treatment. Switzerland is therefore building a safety valve, not a parallel payments network.
For consumers, the practical message is equally clear. Keep a physical card available, remember the PIN and do not assume that a phone-based wallet will provide the same fallback. The planned process is tied to physical debit and credit cards. Meanwhile, cash remains an alternative—one the authorities acknowledge as useful even as they seek additional ways to keep commerce moving. The result is a layered defence: cash, cards and functioning power, each covering a different failure point.
Digital Convenience Meets Swiss Cash Prudence
Switzerland’s payment culture is caught between two instincts: embracing digital convenience while keeping cash close as a safe haven.
That tension gives the offline-card plan unusual importance. The country is highly digitalised in transactions, according to the source, but cash still matters to many people as a fallback when systems fail. The new arrangement does not erase that attachment. Instead, it acknowledges that resilience works best when consumers have more than one way to pay.
The contrast is especially sharp during disruption. Online card payments depend on an active communications chain linking the terminal, payment provider and financial institutions. Cash can bypass that chain, but customers and retailers must have enough of it available. Offline card payments would occupy the middle ground: they preserve electronic purchasing without demanding an immediate network response, provided the terminal is powered and the transaction can later be transmitted.
Northern European countries already have similar systems in place or under rollout, the source reports. Switzerland is now moving in the same direction, adapting its own infrastructure rather than asking the public to obtain new cards. By the end of 2027, the test of resilience will be practical, not ideological: can people still secure necessities when the network cannot answer?
The Real Test Comes at the Till
The 2027 deadline turns a technical fix into a national readiness test.
Before the end of that year, the participating banks, payment service providers and retailers must convert the plan into a dependable operating system for emergencies. Existing readers will need reconfiguration. Staff will need to know when offline mode applies and how customers complete the transaction. Retailers will also need reliable power arrangements, because a battery or generator may be as important as the card terminal itself when the grid or communications infrastructure comes under strain.
Consumers, meanwhile, will need clear expectations. An offline purchase is not an instant settlement: the terminal records it, connectivity returns, and only then does the payment move through the system and debit the account. Physical cards and PINs are essential to the reported process, while digital wallets are not identified as part of the solution.
The initiative will not make Switzerland immune to disruption. It will, however, close a dangerous gap between having essential goods on the shelves and being able to buy them. That is the real promise of the programme. By 2027, resilience will be measured at the till—where a powered terminal, a physical card and a working fallback could keep daily life moving when the network does not.