Switzerland
SNB presses for tougher capital backing of UBS’s global operations
The Swiss National Bank is backing the Federal Council’s tougher plan to require UBS to support foreign units with high-quality Swiss equity. The report should explain the capital debate and its implications for financial stability, UBS competitiveness and taxpayers.
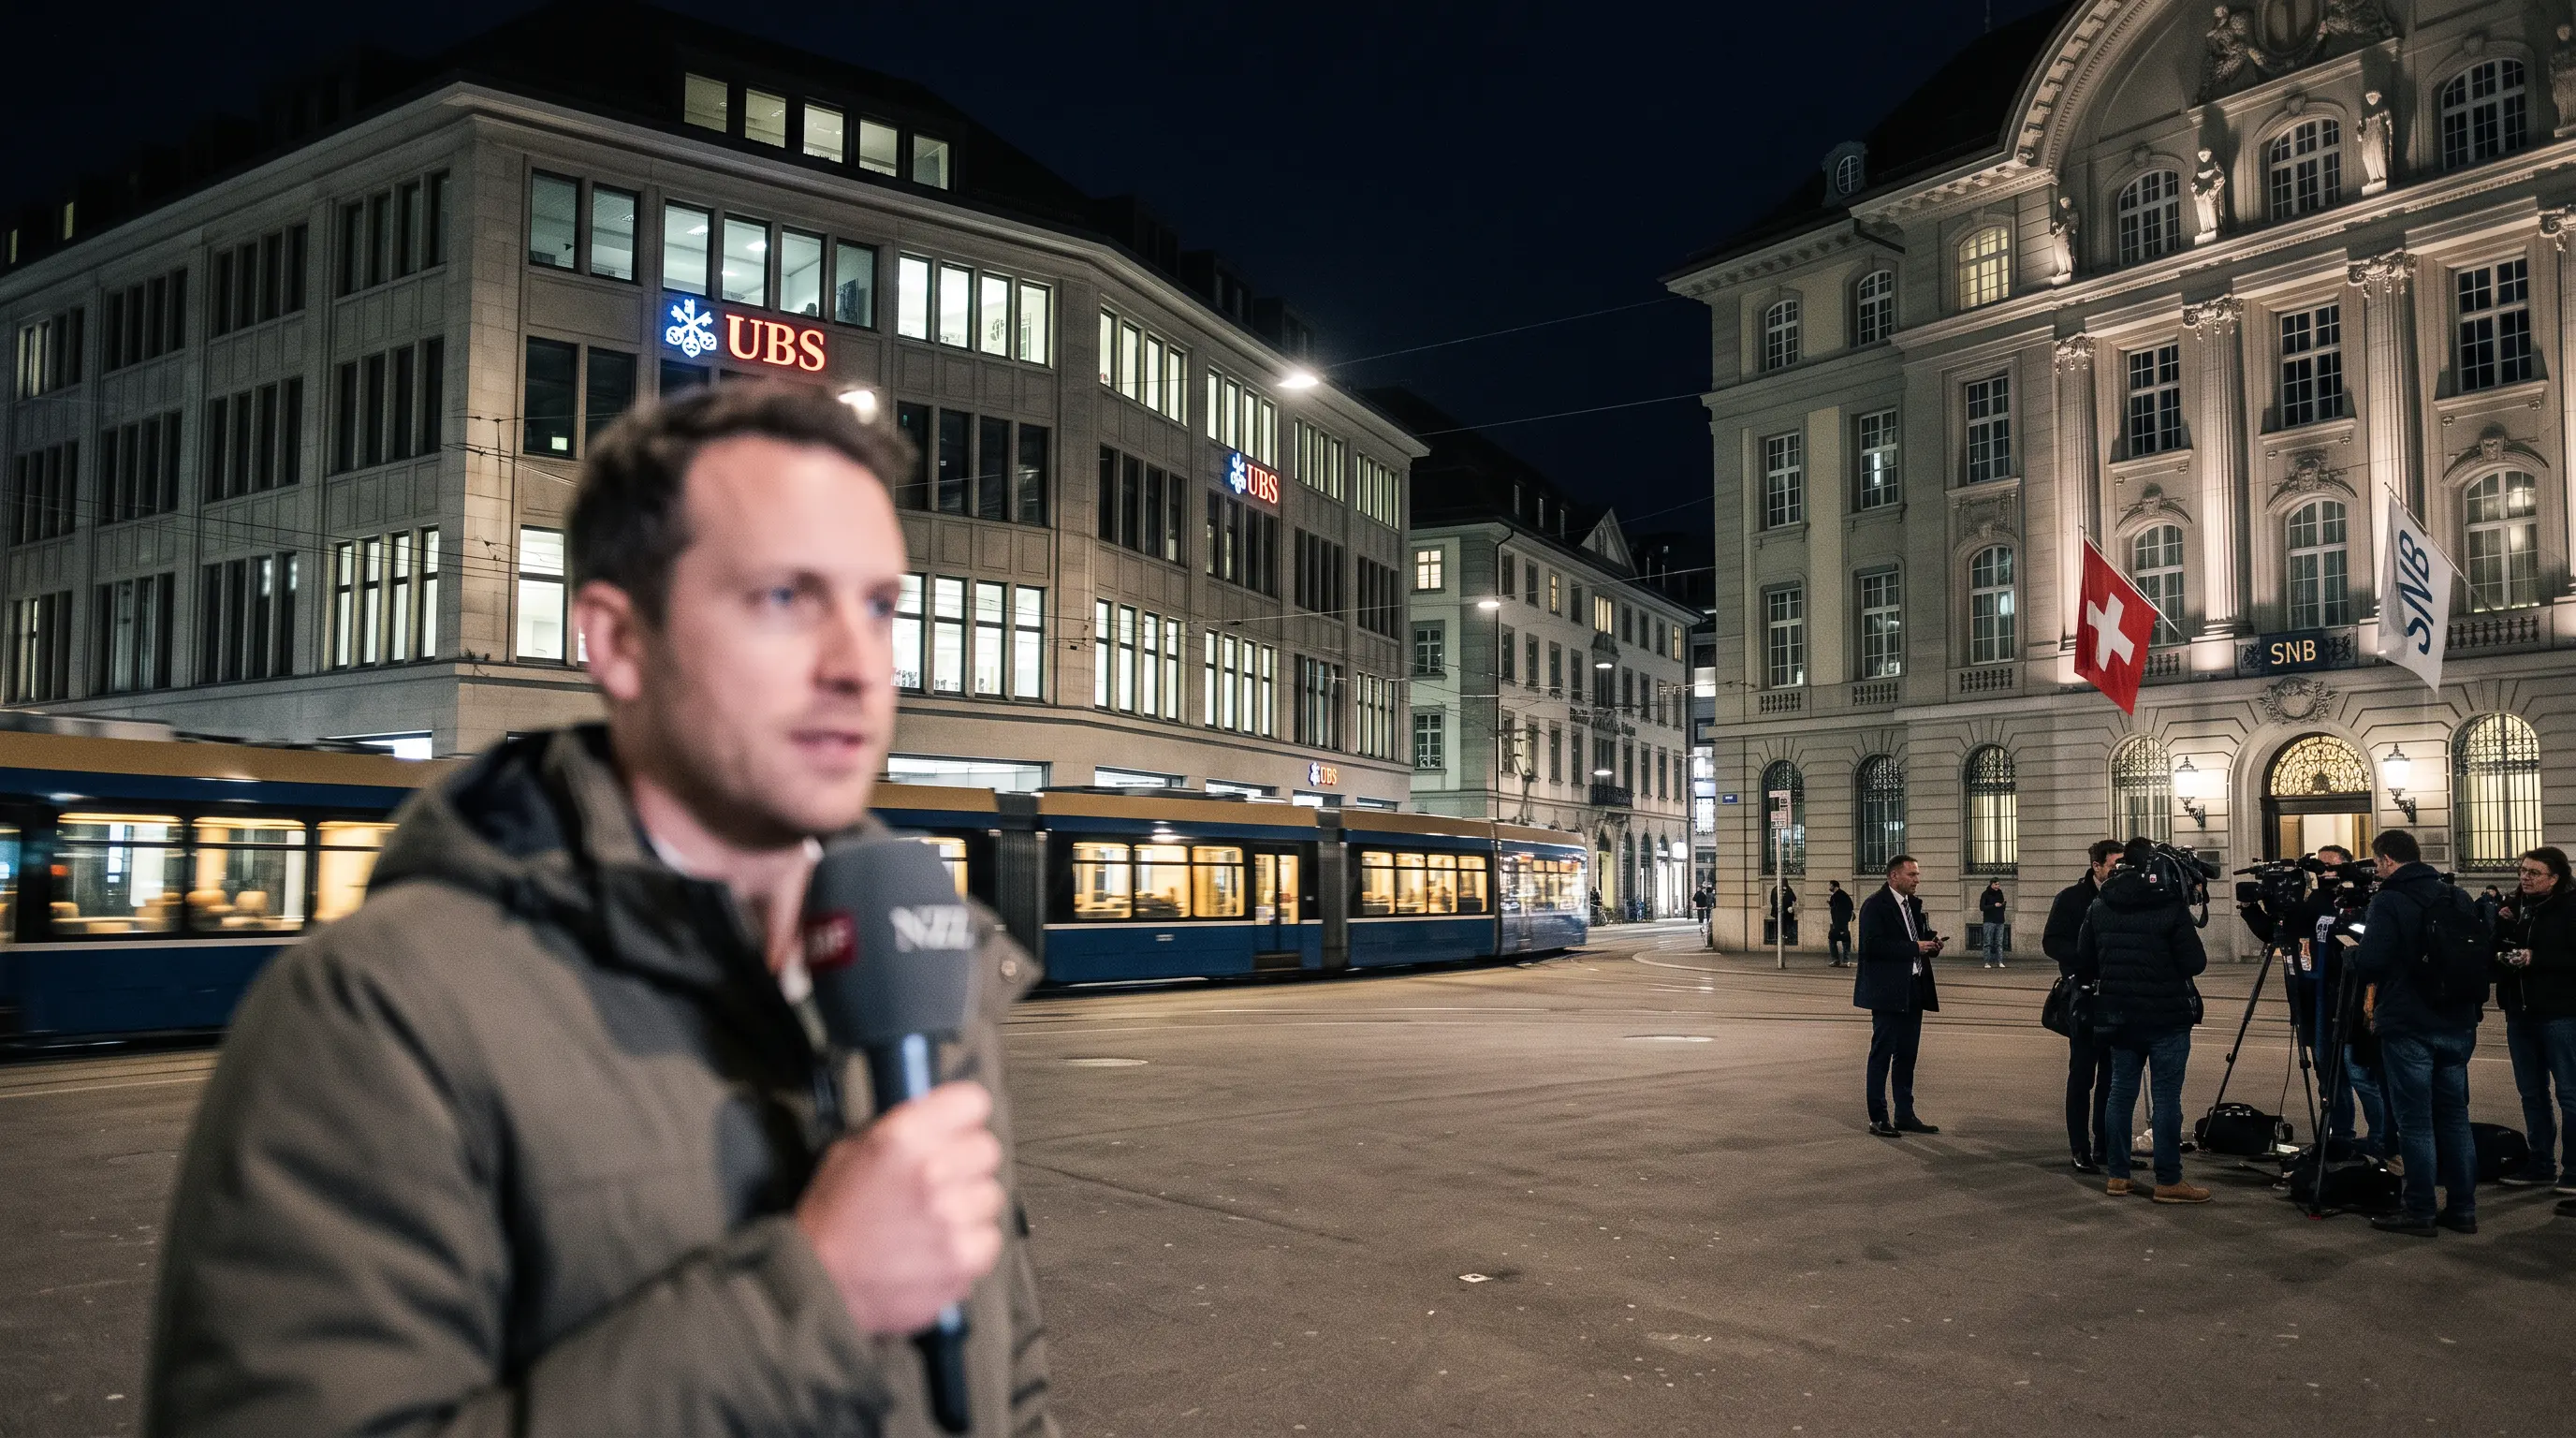
SNB Backs Tougher Capital Rules for UBS
The SNB has entered the UBS capital fight with a clear demand: foreign subsidiaries should be fully backed by high-quality equity held in Switzerland. Antoine Martin, vice-president of the Swiss National Bank and head of its financial stability department, reaffirmed the central bank’s support for the Federal Council’s tougher too-big-to-fail proposal at a public event in Basel.
His intervention arrives as a key committee of the Swiss Senate weighs a compromise that could soften the government’s plan. The decision will shape how Switzerland prepares its largest bank for a future crisis, especially after the collapse of Credit Suisse exposed weaknesses in the country’s resolution framework.
The Federal Council wants UBS to use Common Equity Tier 1, or CET1, capital to support its foreign participations. CET1 consists primarily of shareholders’ equity and retained earnings. It provides a more dependable loss-absorbing buffer than forms of debt that convert or absorb losses only under specified conditions.
Martin said the government’s approach would make the Swiss financial market more resilient. The committee is expected to state its position on Monday, turning a technical dispute over capital instruments into a decisive test of Parliament’s willingness to tighten oversight of UBS.
Parliament Weighs the AT1 Compromise
The proposed compromise could let UBS cover up to half of the requirement with AT1 bonds rather than common equity. That change would reduce the immediate cost of compliance for the bank, but it would also rely more heavily on instruments whose loss-absorbing power depends on contractual triggers and market conditions.
AT1 bonds are designed to convert into equity or suffer losses when a bank’s financial position deteriorates. They can strengthen a balance sheet, yet they do not offer the same straightforward protection as CET1 capital. In a severe crisis, the distinction matters for depositors, counterparties and public authorities seeking to stabilize essential banking services.
The committee’s proposal reflects the political pressure surrounding UBS’s scale and international structure. UBS operates major businesses outside Switzerland, while its home country remains responsible for the framework governing the group’s resilience and potential resolution. Requiring capital to remain in Switzerland would give authorities a clearer buffer to draw on if foreign units came under stress.
UBS has described the government’s plan as “extreme” and warned that it could make the bank less competitive. The compromise seeks to lower that burden, while the SNB argues that the strongest form of capital should remain central to the rule.
Martin Challenges UBS’s Competitiveness Case
Antoine Martin rejected the assumption that stronger capital automatically makes a bank less profitable. In discussion after his Basel speech, the SNB vice-president pointed to the United States, where he said some of the most profitable banks also maintain the highest capital levels.
His argument addresses UBS’s central objection. The bank says the proposed rules could increase its funding costs and put it at a disadvantage against international competitors. Regulators counter that capital is also a source of confidence. A bank financed with a larger share of equity can absorb losses without relying as quickly on emergency measures, asset sales or public support.
The debate carries particular weight in Switzerland. The country’s financial sector is large relative to its economy, and UBS became even more systemically important after it acquired Credit Suisse. That concentration leaves Swiss authorities with limited room for error when setting capital, liquidity and resolution requirements.
Martin’s position does not settle the cost question for UBS. It does establish the SNB’s preferred hierarchy: equity should carry the main burden of protecting the group’s foreign operations, while debt instruments should play a secondary role. Parliament must now decide how closely its compromise follows that standard.
SNB Adds Liquidity and Collateral Safeguards
The SNB supports more than tougher equity rules. Martin’s speech also endorsed a public liquidity backstop in the Federal Council’s package and a quantitative minimum for collateral that central banks can accept from systemically important institutions.
Those measures target a different pressure point in a banking crisis. Capital absorbs losses over time, while liquidity allows a bank to meet withdrawals and settle payments when confidence falls. Eligible collateral gives a central bank greater assurance that emergency lending can be secured if market funding dries up.
Together, the proposals would expand Switzerland’s toolkit after the Credit Suisse failure. They would also clarify the obligations of a bank whose activities, employees and clients span several jurisdictions. A stronger domestic capital base cannot eliminate every risk at a global institution, but it can give Swiss authorities more options during a fast-moving shock.
The next step belongs to Parliament. The Senate committee’s expected position on Monday will indicate whether lawmakers retain the Federal Council’s full CET1 requirement or permit a wider role for AT1 bonds. The final rules will determine how UBS finances its international footprint and how much protection Switzerland demands before that footprint can rely on the Swiss safety net.