Syngenta
Syngenta lifts operating profit despite weaker first-half sales
Basel-based Syngenta increased first-half EBITDA by 2% despite a 2% decline in turnover to $12.2 billion. The agribusiness group attributed the improvement to higher-value sales and stronger profitability, while lower-margin grain trading in China weighed on revenue.
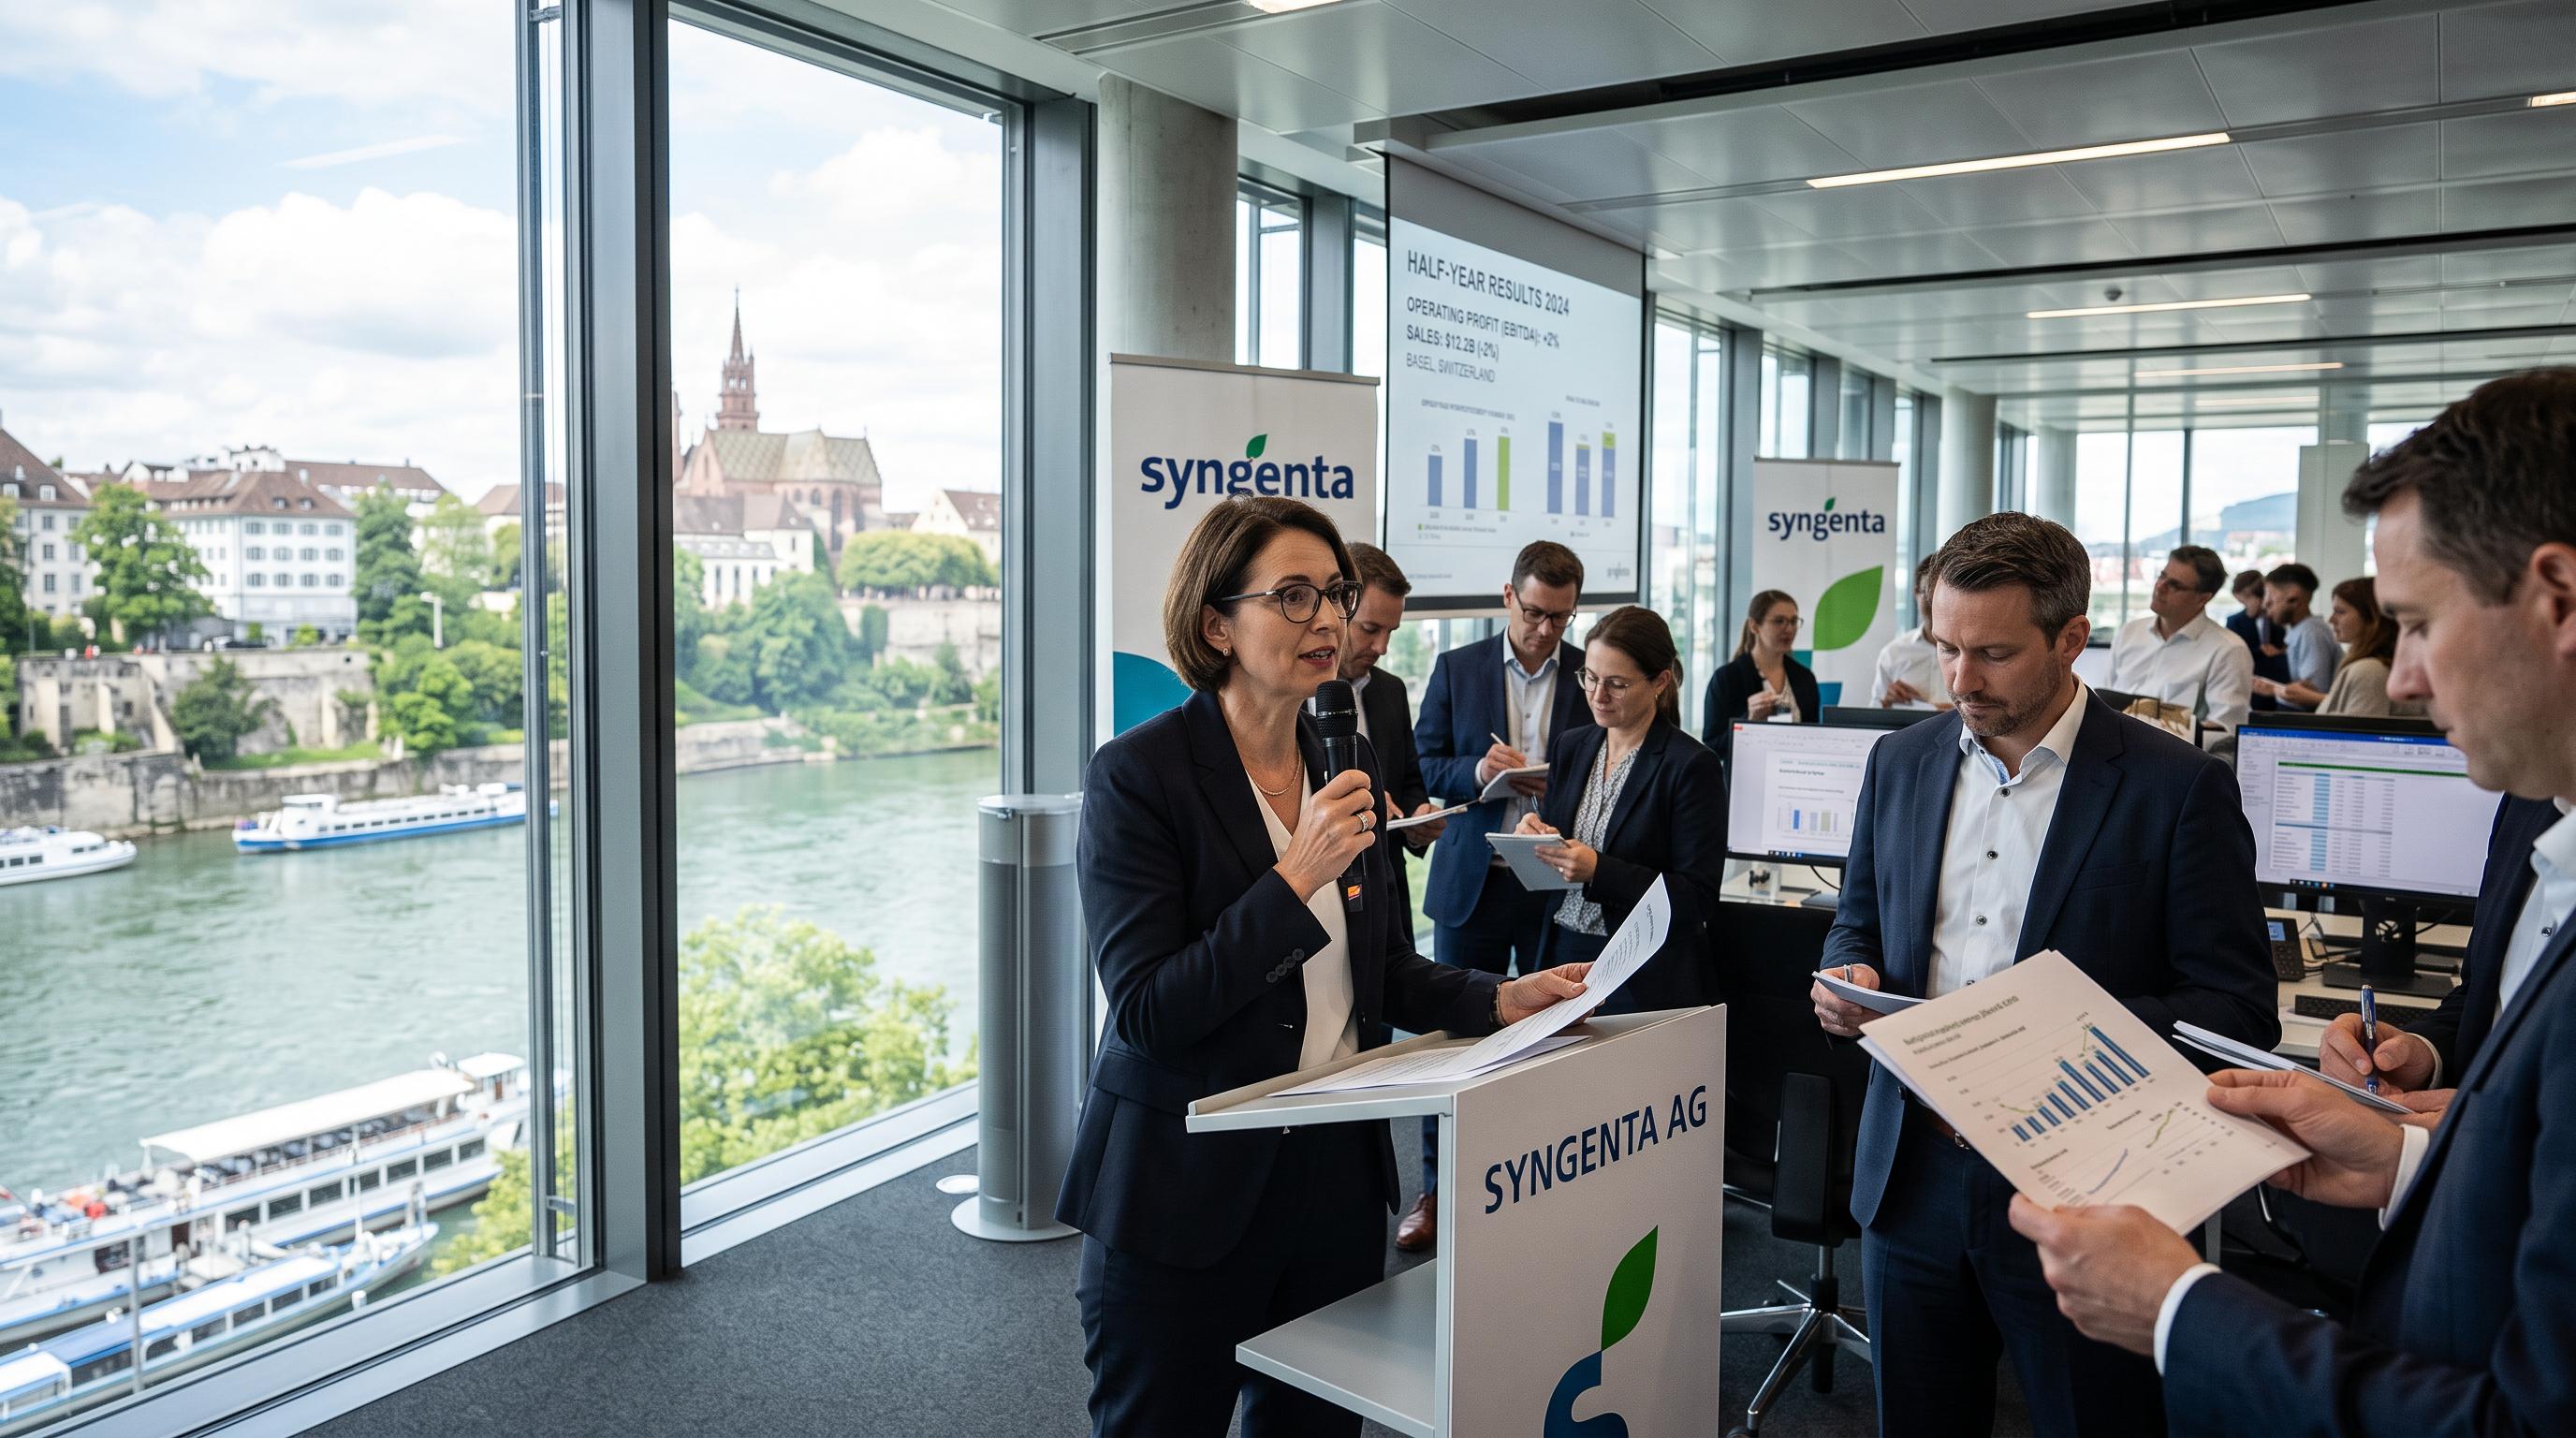
Syngenta protects profit as sales soften
Syngenta lifted first-half EBITDA 2% to $2.4 billion, even as the Basel-based agribusiness group reported weaker sales. Turnover declined 2% year on year to $12.2 billion between January and June 2026, according to figures released on Thursday, August 27.
The result shows how the group is reshaping its business mix as it faces uneven demand across agricultural markets. Syngenta said higher-value sales and stronger profitability across all business divisions helped offset lower revenue. At constant exchange rates, turnover would have fallen by 7%, highlighting the effect of currency movements on the reported result.
The main drag came from China, where Syngenta reduced its exposure to lower-margin grain trading. That decision cut revenue, but it also improved the quality of the group’s sales mix. The company’s EBITDA margin rose 0.9 percentage points to 19.5%.
For Switzerland, the figures put the performance of one of the country’s most prominent industrial groups in focus. Syngenta’s Crop Protection business is based in Basel, while the wider group operates across seeds, crop protection, biological products and agricultural distribution. Its results also offer a snapshot of how global farm input companies are responding to volatile crop economics and regional shifts in planting.
Crop protection carries the growth
Crop protection revenue rose 4% to $6.6 billion, making it the strongest reported growth area in Syngenta’s first-half portfolio. The division sells products designed to protect crops from weeds, insects and disease, and remains central to the group’s earnings model.
Sales in Europe increased 8%, despite recent heat and drought that weakened demand in parts of the region. The regional result suggests that farmers continued to invest in crop protection, even as weather conditions complicated planting and growing decisions. Demand can vary sharply by crop, geography and season, making the timing of applications important for suppliers and growers alike.
The European performance also matters to Switzerland, where Syngenta’s Basel operations anchor the group’s crop protection business. The company develops and commercialises products in a sector closely watched by regulators, farmers and environmental groups across the continent.
Syngenta’s first-half figures do not provide a detailed breakdown of individual products or volumes. They do show that the group’s strategy is favouring businesses with stronger margins. By directing activity towards higher-value crop protection sales, Syngenta improved profitability while overall group turnover declined. That shift may help cushion the company against weaker commodity-linked activity, although agricultural demand remains exposed to weather, farm income and changing rules on chemical use.
Seed sales reveal a regional divide
Seed revenue reached $2.5 billion, up 1% from the same period a year earlier, but regional results diverged sharply. Brazil delivered the standout performance, with seed revenue increasing 18%. North American revenue fell 13%, which Syngenta linked to a decline in US maize acreage.
The split reflects the different planting decisions confronting farmers in major agricultural markets. Brazil remains a key growth market for crop genetics and seeds, supported by its large-scale soybean, maize and other commodity production. In the United States, a smaller maize area reduced demand for Syngenta’s seed products during the first half.
Seeds are strategically important because they can generate higher-value, technology-driven revenue than commodity trading. The business also gives suppliers a direct stake in farmers’ decisions about crop varieties, yields and resilience. Those decisions are increasingly influenced by drought, heat, disease pressure and commodity prices.
Syngenta’s overall seed growth remained modest because strong Brazilian sales did not fully compensate for the North American decline. The numbers underline the geographic risk in global agribusiness. A successful season or planting cycle in one hemisphere can coincide with weaker acreage or lower demand in another, leaving companies to balance research investment, inventories and distribution across markets.
China cuts volume to improve returns
China revenue dropped 15% after Syngenta pulled back from low-margin grain trading, making the country the largest source of pressure on group turnover. Syngenta Group China generated about $2.5 billion, or roughly one-fifth of the group’s revenue, and is reported as a separate entity.
Grain trading can add substantial sales volume without producing the same profitability as crop protection, seeds or other specialised agricultural products. By reducing that activity, Syngenta accepted lower reported revenue while concentrating more heavily on businesses with better returns. The change helps explain why EBITDA increased as turnover declined.
China remains central to Syngenta’s corporate identity and commercial footprint. The group is headquartered in Switzerland but Chinese-owned, and its activities span agricultural inputs and distribution in one of the world’s largest farming markets. ChemChina acquired Syngenta AG in 2017, creating a corporate structure with Swiss, Chinese, American and Israeli operations.
The revenue decline also arrives during a leadership transition. In early August, Hengde Qin became the first Chinese national to take the top job at Syngenta Group. His appointment places the company’s China strategy, international operations and profitability agenda under a new leader as the group continues to simplify its sales mix.
Basel watches the margin strategy
A 19.5% EBITDA margin gives Syngenta room to manage uneven agricultural demand, but the first-half figures also expose the limits of relying on global scale. The group improved operating profit through a more selective business mix, while currency effects and lower Chinese trading revenue pulled down reported sales.
The next phase will test whether stronger margins can persist across the full year. Crop protection demand held up in Europe and seed sales expanded in Brazil, yet North American maize acreage weakened and Chinese revenue contracted. Weather remains a variable for every major growing region. Heat and drought can delay applications, reduce planting and alter farmers’ spending priorities within a single season.
Switzerland will continue to matter to the group’s direction. Basel houses the headquarters of Syngenta Crop Protection, and the company remains one of the largest Swiss-based names in the international agricultural sector. Its ownership and operating structure connect Swiss research and management with Chinese capital, US seed operations and Israeli agricultural products through Adama.
Syngenta’s first-half performance therefore points to a measured corporate adjustment rather than a broad expansion in demand. The group is prioritising profitability and higher-value products, accepting lower turnover where volume does not justify the return. Investors and agricultural customers will watch whether that discipline can withstand the next cycle in planting, weather and farm incomes.