Vaud
Vaud approves major income and wealth tax reduction
Vaud voters have approved a 12% reduction in income and wealth taxes. Although the decision will lower the canton’s tax burden, Vaud is expected to remain above the Swiss average, making the vote a significant test of cantonal tax competition rather than a transformation into a tax haven.
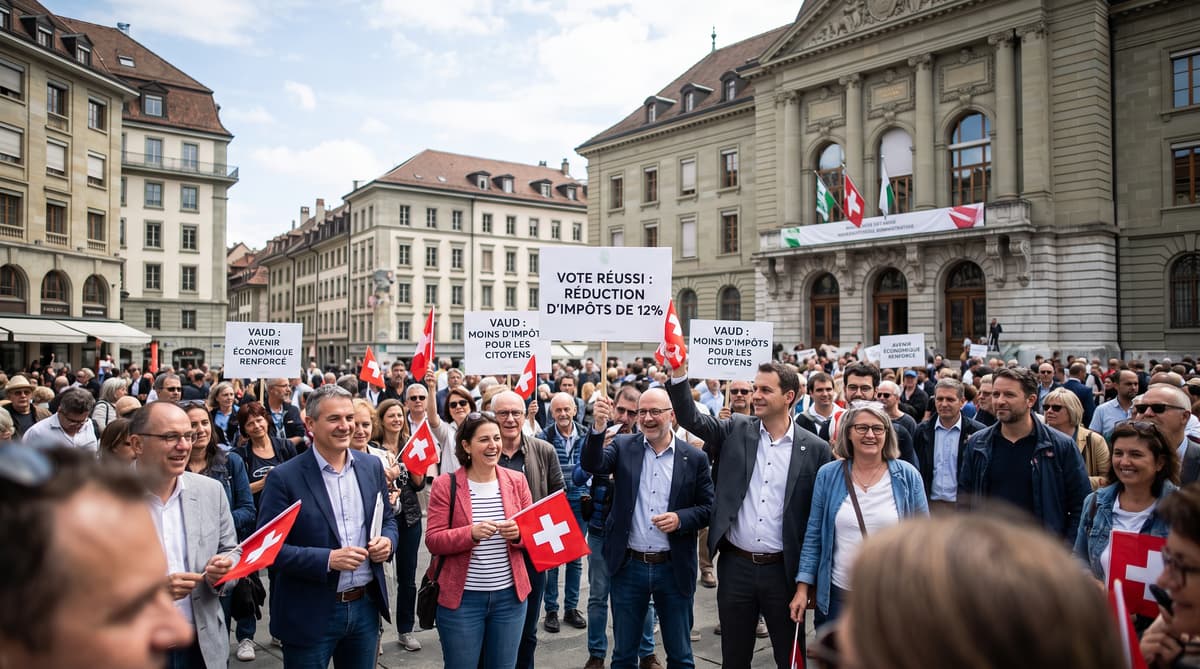
53.1% of Vaud voters backed a 12% reduction in income and wealth taxes in the cantonal referendum held on Sunday, September 27, 2026. The result gives households some relief and sends a clear signal to the canton’s political establishment as tax competition intensifies across Switzerland.
The reduction will lower Vaud’s tax burden from 2027. It will not fundamentally change the canton’s position in the national rankings. Residents, particularly those with middle and upper middle incomes and substantial assets, will continue to face tax bills above the Swiss average.
Vaud has long financed an extensive network of public services and redistribution through progressive personal taxation. The model supports spending on health, welfare, education and infrastructure, especially in urban areas. Those commitments have helped place Vaud alongside Geneva and Basel City among Switzerland’s three most heavily taxed cantons by several measures.
The vote therefore marks a shift in the balance between revenue and competitiveness. It gives taxpayers a reduction while leaving Vaud inside the group of high tax cantons. For companies and mobile residents comparing locations, the measure will be one factor in a wider calculation that includes housing, transport, public services and labour markets.
The Cut Still Leaves Vaud Among Switzerland’s Highest Tax Cantons
Vaud will remain above the Swiss average after the reform, according to the assessment of the vote’s fiscal impact. The canton is expected to stay near the top of the tax table for people with more than CHF 100,000 in taxable income or wealth.
That distribution matters politically. A broad percentage reduction can produce different effects for households depending on income, assets, deductions and family circumstances. The relief will be visible in tax bills, yet it will not erase the gap between Vaud and lower tax cantons. Middle and upper middle income earners, as well as wealthier residents, are likely to remain under heavier pressure than comparable taxpayers elsewhere in Switzerland.
The result also leaves Vaud’s public finance debate open. The canton’s high tax rates reflect a deliberate choice to fund relatively extensive services and redistribution. Cutting rates reduces revenue unless spending falls, economic activity expands, or other sources compensate for the difference. The source material does not provide a projected cost for the reform, so its precise effect on the cantonal budget remains a matter for future financial reporting.
For residents, the immediate issue is straightforward: the tax burden will fall. For policymakers, the longer calculation concerns how much revenue Vaud can surrender while maintaining the services that underpin its current fiscal model.
The Next Fight Will Be Over Tax Brackets
The next Vaud tax battle is already taking shape around the system of tax brackets introduced in 1987. Business groups and the political right are not currently preparing another immediate campaign for personal tax cuts. Their attention is turning towards a structural change that will affect married couples across Switzerland.
Swiss voters approved a move towards individual taxation in March. Under that model, spouses would be assessed individually rather than through the existing system for married couples. The cantons must implement the reform by January 1, 2032, giving Vaud several years to redesign its brackets, deductions and administrative processes.
That timetable places tax architecture alongside tax rates in the political debate. A percentage reduction can be legislated and communicated quickly. Reworking brackets requires decisions about how different households are treated, how revenue is distributed, and whether reforms shift the burden between single people, married couples, families and high earners.
Vaud’s finances will add pressure to those choices. The canton is already facing growing strain, and the approved reduction will make the next budget discussions more consequential. The issue is likely to return after the next cantonal elections in summer 2027, when parties can campaign on the fiscal effects of the reform and on the design of the new individual taxation system.
French Speaking Switzerland Joins the Tax Competition
Western Switzerland is moving through a broader cycle of tax reductions and fiscal reassessment. Vaud’s decision follows measures and proposals in several neighbouring cantons, where personal taxes have traditionally been higher than in much of German-speaking Switzerland.
Geneva introduced an average 8% income tax cut in 2025, yet its worsening fiscal position has reopened debate over the direction of policy. Geneva Finance Minister Nathalie Fontanet has said that all options remain available, including tax increases.
Valais has offered tax relief to taxpayers defined by the cantonal parliament as middle class since last year and has expanded household deductions. Bern is preparing a revision that could reduce taxes for some low and middle income earners by as much as 20%, with changes due to begin in 2027. In Neuchâtel, representatives of the Swiss People’s Party, the Liberals and the Centre submitted an initiative in July 2025 seeking a 10% cut in personal income tax rates by 2030.
The regional pattern reflects competition for residents and political pressure over living costs. It also exposes the limits of rate cutting when public spending remains high. Cantons are testing how far they can ease household burdens while financing services that voters continue to expect. Vaud’s referendum adds another important case to that national comparison.
The 2027 Elections Will Test Vaud’s Fiscal Strategy
Vaud’s tax burden will fall from 2027, while the canton’s fiscal choices remain under scrutiny. The referendum gives voters a concrete reduction, but it does not remove the structural reasons Vaud ranks among Switzerland’s high tax jurisdictions. The canton will continue to fund broad public services through progressive taxation, and its position will remain relevant to households weighing where to live and work.
The next phase will combine implementation with political accounting. Cantonal officials will need to apply the 12% reduction, monitor its effect on revenue and explain how the public budget will absorb the change. Parties will then approach the 2027 elections with a record to defend or challenge.
The national timetable adds another layer. By January 1, 2032, Vaud must also adapt to individual taxation for married couples. That reform could reshape the tax treatment of households and force a wider review of brackets and deductions.
For Switzerland, the Vaud vote reinforces a trend rather than announcing a new tax haven. Cantons across the country are adjusting rates, deductions and tax structures as they compete for taxpayers and respond to budget pressure. Vaud has moved in that direction, while keeping its established high service, high tax model largely intact.