housing
Swiss housing vacancy rate falls below 1%
Switzerland’s housing vacancy rate has fallen below 1% for the first time since 2013, with fewer than 45,500 homes empty on June 1. The tightening market is increasing pressure on tenants and intensifying concerns about housing affordability and supply.
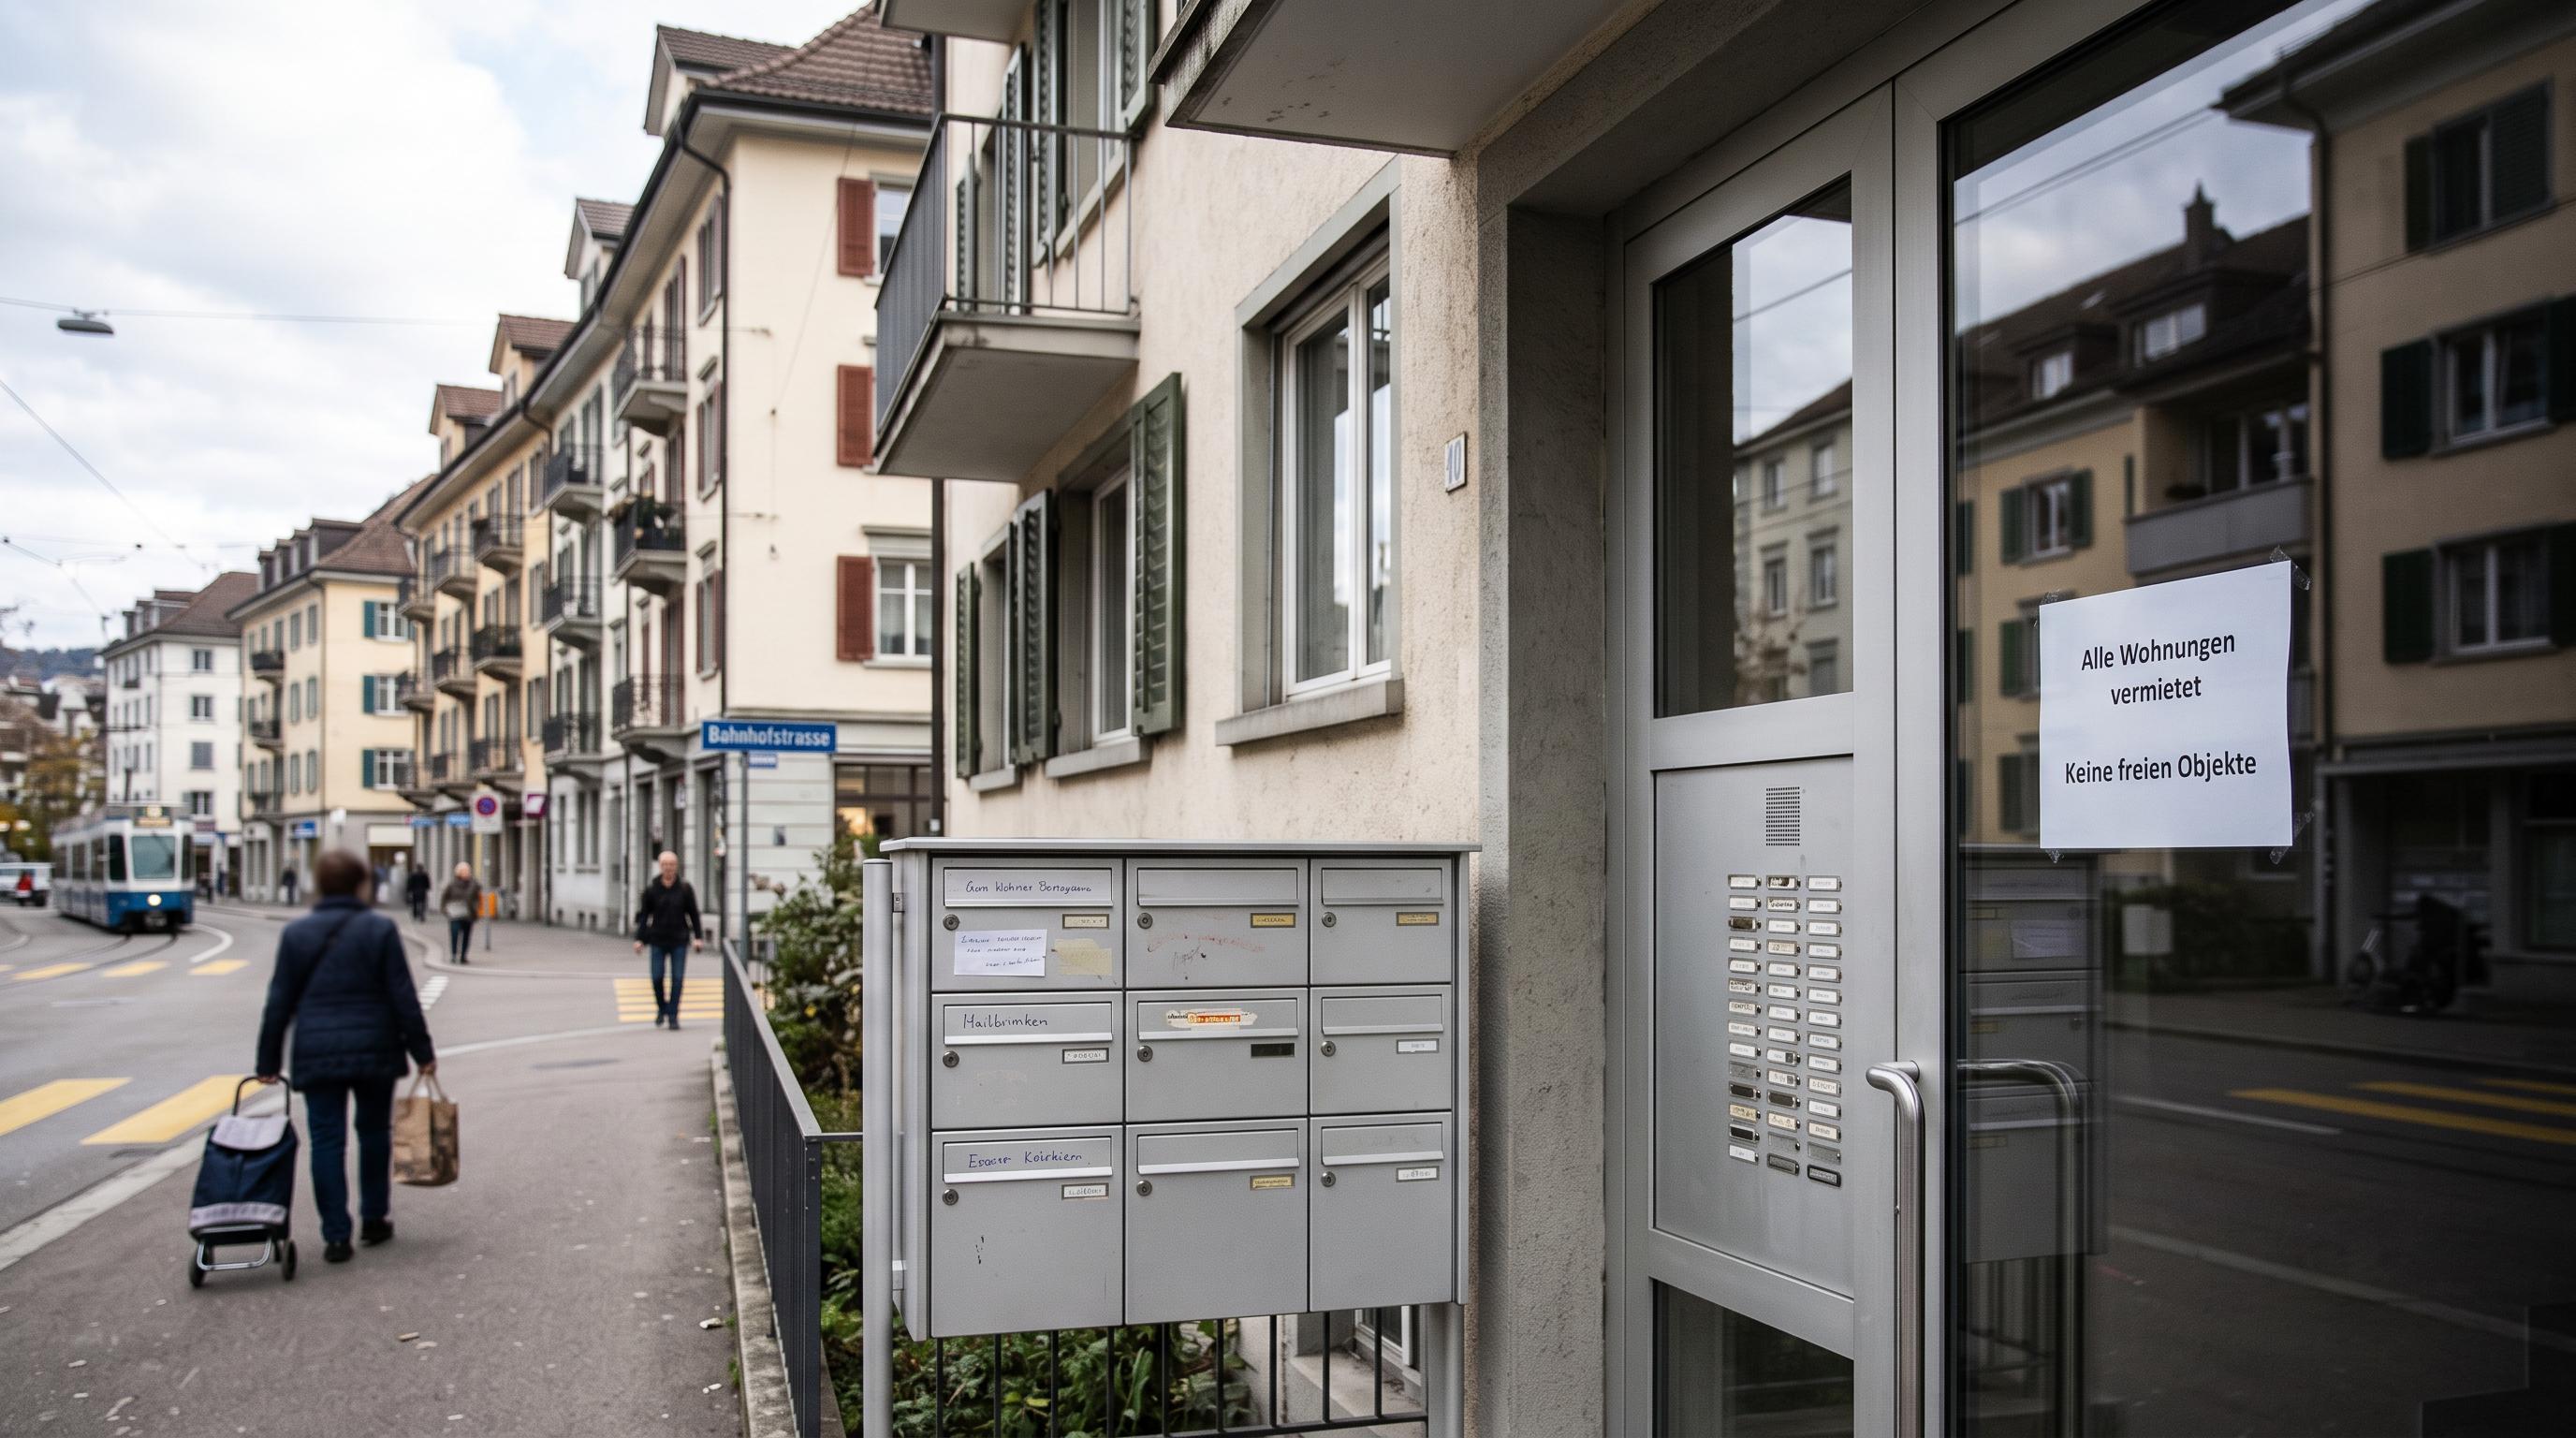
Switzerland’s Empty Homes Fall Below 1%
Switzerland had 45,493 empty homes on June 1, 2026, equal to a vacancy rate of 0.93%. The figure, published by the Federal Statistical Office, marks the country’s first sub-1% rate since 2013 and confirms a housing market that has tightened for six consecutive years.
The annual change is small in percentage terms, but significant for people searching for a flat in the country’s most constrained markets. The number of vacant homes fell by 2,962, or 6.1%, compared with the previous year. Since 2021, the national vacancy rate has declined by 0.79 percentage points.
The available stock is also weighted toward the rental market. 34,690 homes were offered for rent, while 10,803 were available for sale. That leaves fewer options for households facing lease renewals, relocations or rising mortgage costs.
The shortage reaches beyond the headline total. Vacancies declined among homes of every size, with two-room flats recording the steepest percentage fall. These smaller units are particularly important for single-person households, students and older residents who need to remain near jobs, transport and services. The latest figures place housing supply firmly among Switzerland’s most immediate cost-of-living pressures.
Cantons Feel the Shortage Unevenly
Fifteen cantons now have vacancy rates below 1%, exposing sharp differences in access to housing across Switzerland. Zug recorded the country’s lowest rate at 0.20%, followed by Geneva at 0.31% and Obwalden at 0.38%. Vaud stood at 0.87%, making it the only canton in French-speaking Switzerland apart from Geneva to fall below the national threshold.
The pressure is especially intense in economically attractive and space-constrained areas. Uri, Schwyz, Zurich, Nidwalden, Lucerne, Glarus, Graubünden, Basel-Landschaft, Basel-Stadt and Schaffhausen also recorded rates below 1%.
Jura remained the outlier, with the highest vacancy rate at 3.35%. Solothurn followed at 1.91%, then Ticino at 1.78% and Neuchâtel at 1.64%. A higher rate does not automatically mean that homes are affordable or located where demand is strongest, but the regional gap shows how unevenly housing pressure is distributed.
Six of Switzerland’s seven major regions recorded lower vacancy rates. Eastern Switzerland, north-western Switzerland and Ticino saw the sharpest declines. Greater Zurich was the exception, edging up to 0.52%, although that still represents a highly constrained market.
Institutional Owners Gain Ground
Institutional investors owned about 44% of Switzerland’s rental housing in 2023, up from roughly 31% in 2000. Pension funds, insurers and property companies expanded their share as private and non-profit landlords lost ground. The shift has unfolded alongside a sustained fall in available homes and rising rents.
The ownership trend matters because tenants encounter the housing market through monthly payments, lease conditions and competition for each available flat. In areas where vacancy rates are close to zero, households have little room to negotiate and may remain in unsuitable homes because moving would mean higher rent or a long search.
The national figures also show that supply is tightening across different kinds of property. On June 1, 6,496 detached houses were empty, while 3,910 homes built within the previous two years had not yet been occupied. Vacancies fell among both newly built homes and detached houses, suggesting that the squeeze is not confined to one segment of the market.
Rents are shaped by location, quality, regulation and ownership, so the national vacancy rate cannot explain every lease increase. It does, however, provide a clear measure of how little slack remains in the system. A household looking for a home in Zug, Geneva or parts of Zurich faces a very different market from one searching in Jura or Solothurn.
Tenants Challenge the Price of New Supply
The Swiss Tenants’ Association says new construction is failing to relieve pressure for many households because much of it sits at the expensive end of the market. The association argues that cheaper homes are steadily disappearing even as developers add new units.
That criticism goes to the composition of supply, not simply its volume. A newly built flat can increase the national housing stock while remaining out of reach for families, lower-paid workers, students or pensioners. Location also matters. Construction far from major employment centres may offer little relief to people who cannot afford longer commutes or higher transport costs.
The association has also accused some landlords of demanding excessive rents and breaching legal limits on returns. Those are serious allegations that depend on the facts of individual properties and leases. They point to the legal and political tension created by a market in which tenants have few alternatives.
The vacancy data reinforces the association’s concern. Rental vacancies fell 6.7% in one year, compared with a 4.1% decline in homes available for sale. The steepest percentage fall occurred among two-room flats, a category with strong demand from small households. For tenants, the immediate challenge is finding a home that is both available and affordable, rather than simply counting new construction projects.
Switzerland Faces the Next Supply Test
A vacancy rate of 0.93% leaves Switzerland with little spare capacity as population, employment and household demand continue to change. The next phase of the housing debate will focus on where new homes are built, who can afford them and how quickly they reach the market.
Policymakers face different conditions from canton to canton. Zug and Geneva need additional capacity in markets where available homes are exceptionally rare. Jura and Solothurn have more vacant stock, yet those homes may not match demand by location, size, condition or price. National averages can identify the direction of travel, but local planning decisions determine whether households find a workable option.
The figures also give political weight to calls for faster construction, denser development around public transport and stronger protection for tenants. Each measure involves trade-offs over land use, infrastructure, neighbourhood character and public finances. The Swiss Tenants’ Association is pressing for supply that reaches ordinary budgets, not only the premium segment.
For renters, the immediate outlook remains difficult. Rental vacancies are falling faster than sales vacancies, and the national rate has declined every year since 2020. Unless new homes become available in the places and price bands where demand is strongest, the competition for leases will remain intense across much of Switzerland.